How to set up your surplus
Work through the planner, including tagging shared accounts, coverage and Shared Pool.
Screenshots use fictional accounts and example amounts. Select any image to open it full size.
Get started
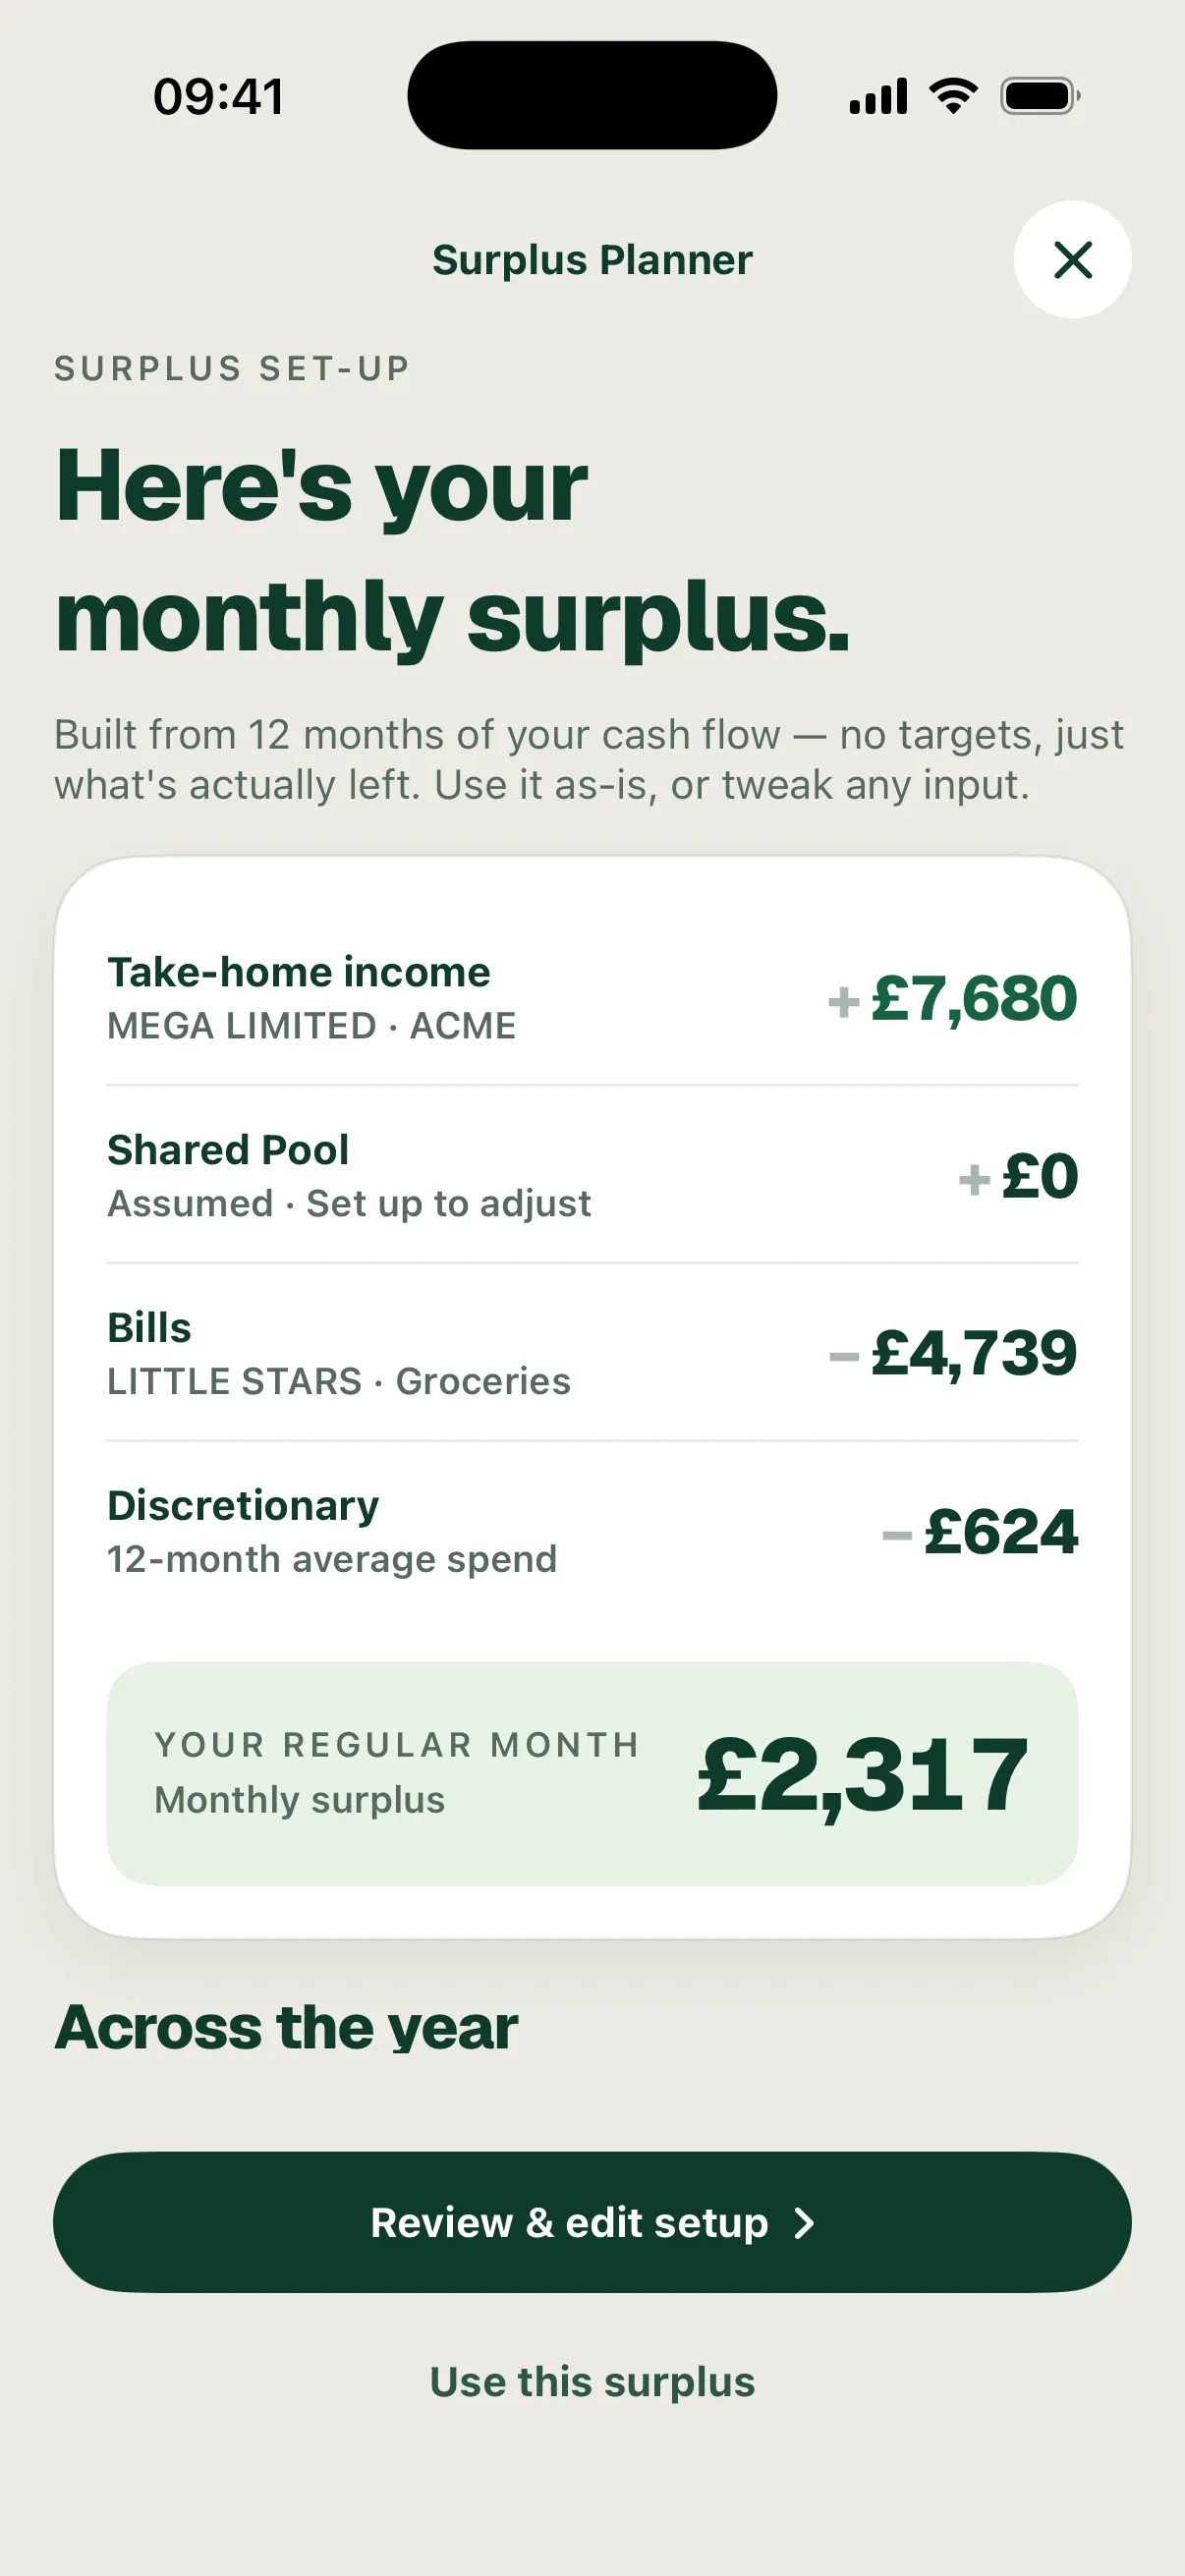
Open Open surplus setup on Home, or Edit surplus in Growth after setup. The introduction shows a starting calculation from 12 months of your cash flow: take-home income, Shared Pool, bills and discretionary spend, with the typical monthly surplus underneath. Choose Review & edit setup to work through the steps. On an existing plan, the same option reads Edit surplus setup.
The example household has two linked banks. A Monzo current account receives a £3,480 ACME salary and a Barclays current account, the joint account, receives a £4,200 MEGA LIMITED salary. Together they give £7,680 of take-home income, £4,739 of bills and £624 of discretionary spend, so the starting household surplus is £2,317 a month.
Step 1: Household
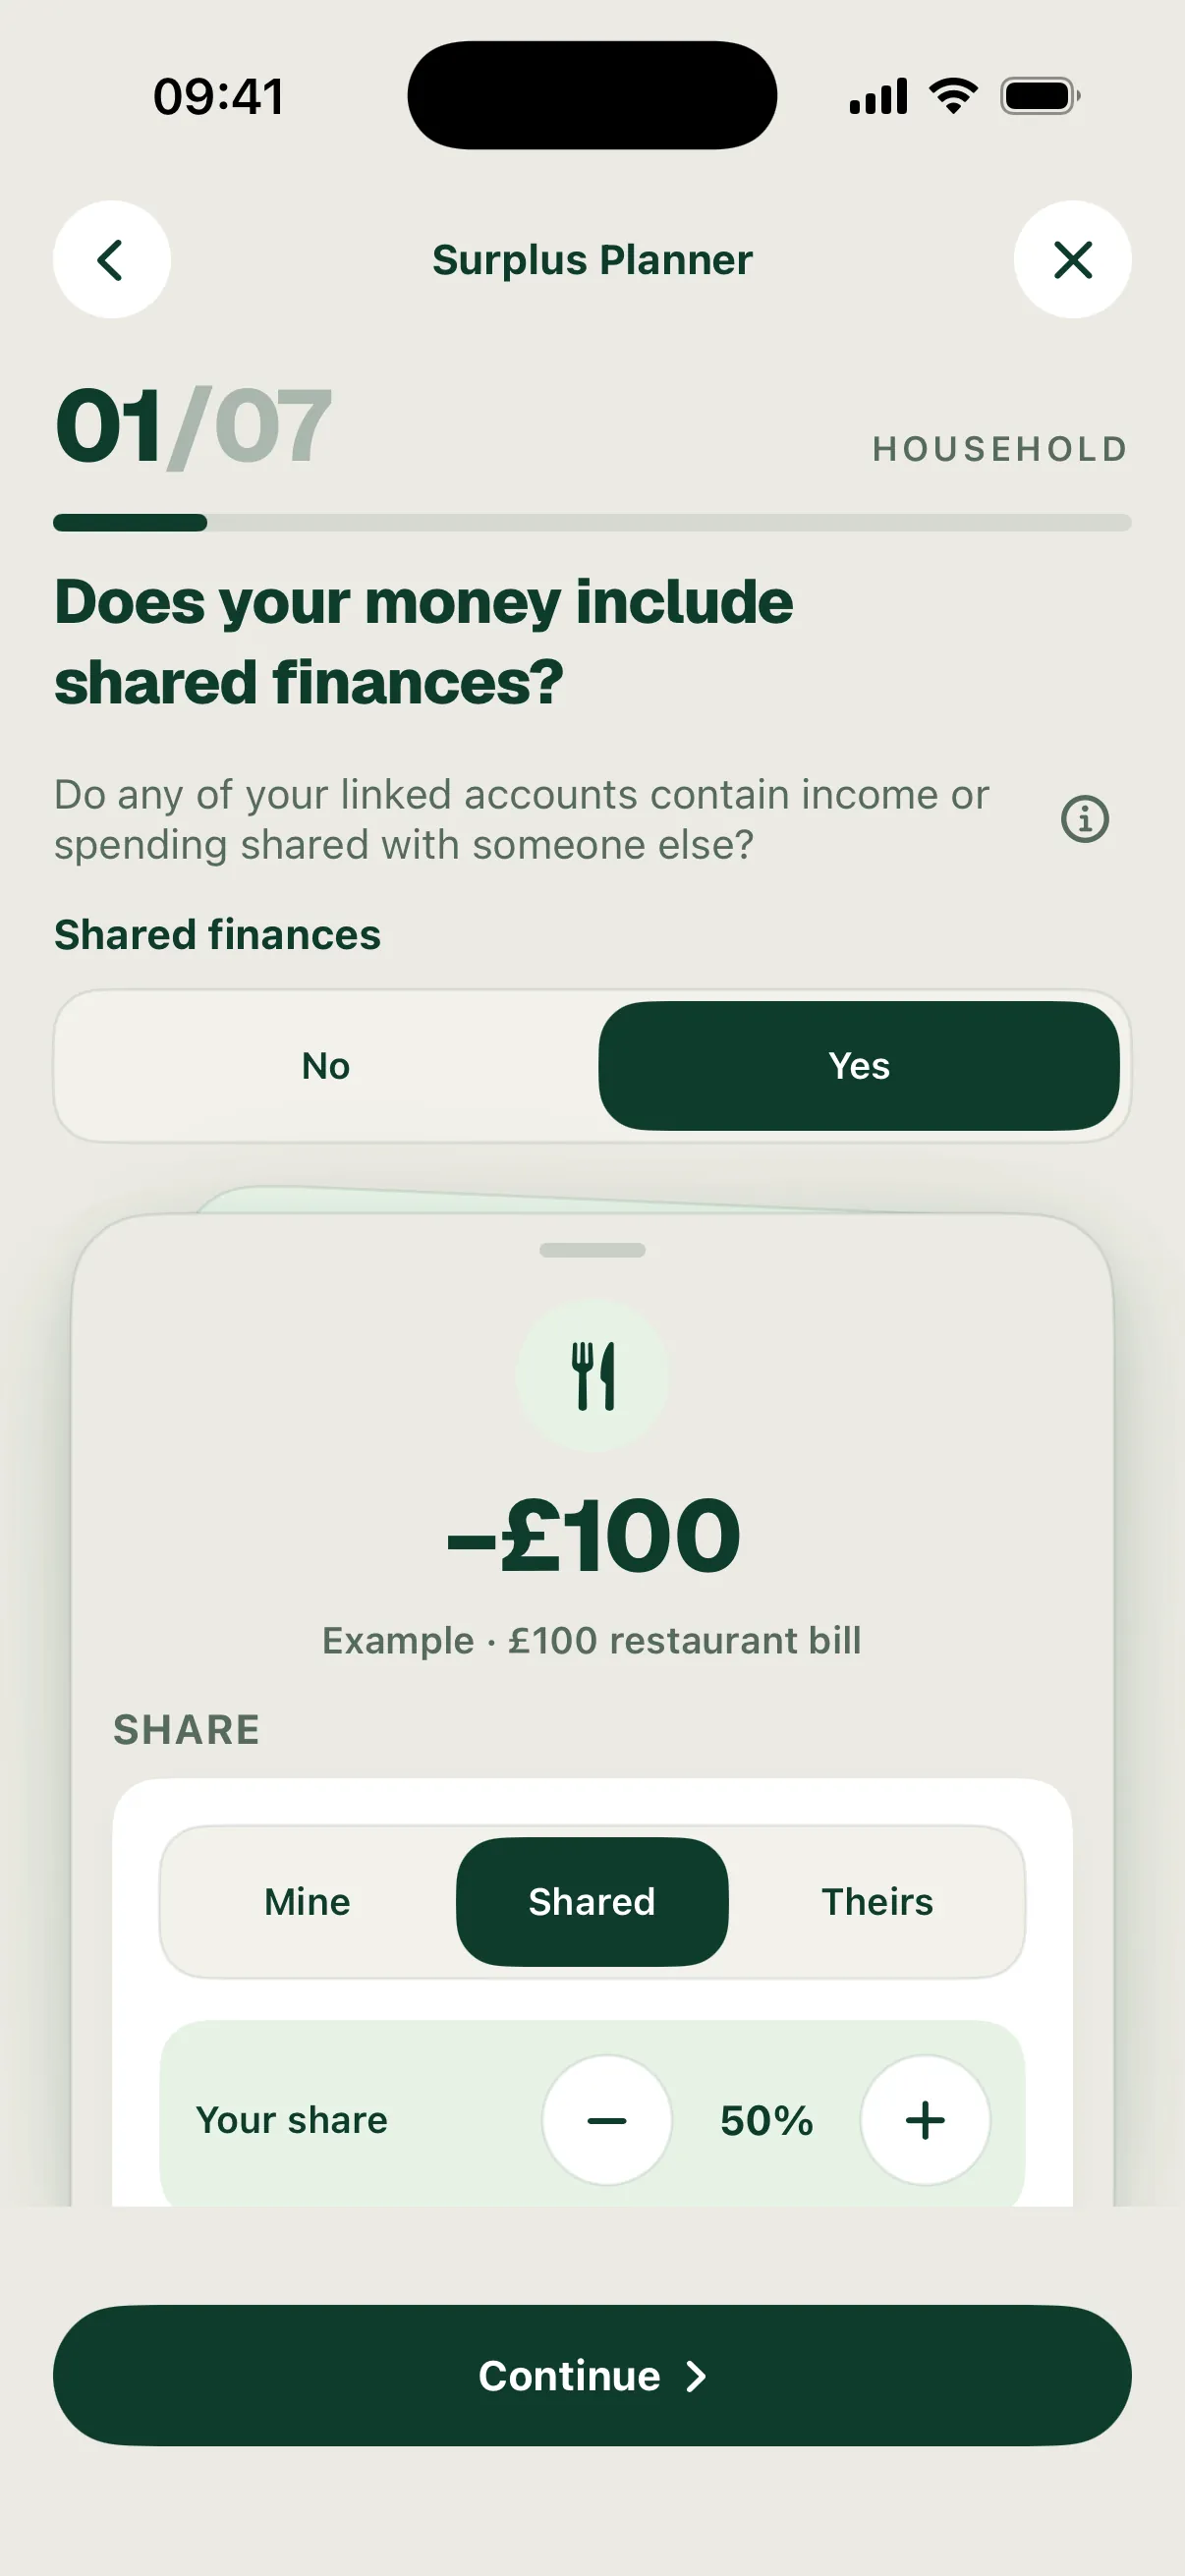
Choose Yes when any linked account contains income or spending shared with someone else, for example a joint account used for salaries, bills or everyday spending. Choose No when your linked accounts hold only your own money. With No, the planner has five steps. With Yes, it adds two: tagging your accounts and checking coverage.
The card under the question is a live example of what tagging does. A £100 restaurant bill in an account tagged Mine is all yours. In an account tagged Shared, a Your share stepper appears and your share of the bill follows it, so at 50% the bill counts £50 towards your number. Tagged Theirs, none of it lands in your number. In a shared account you can change any transaction’s split later, from its edit sheet.
Step 2: Accounts
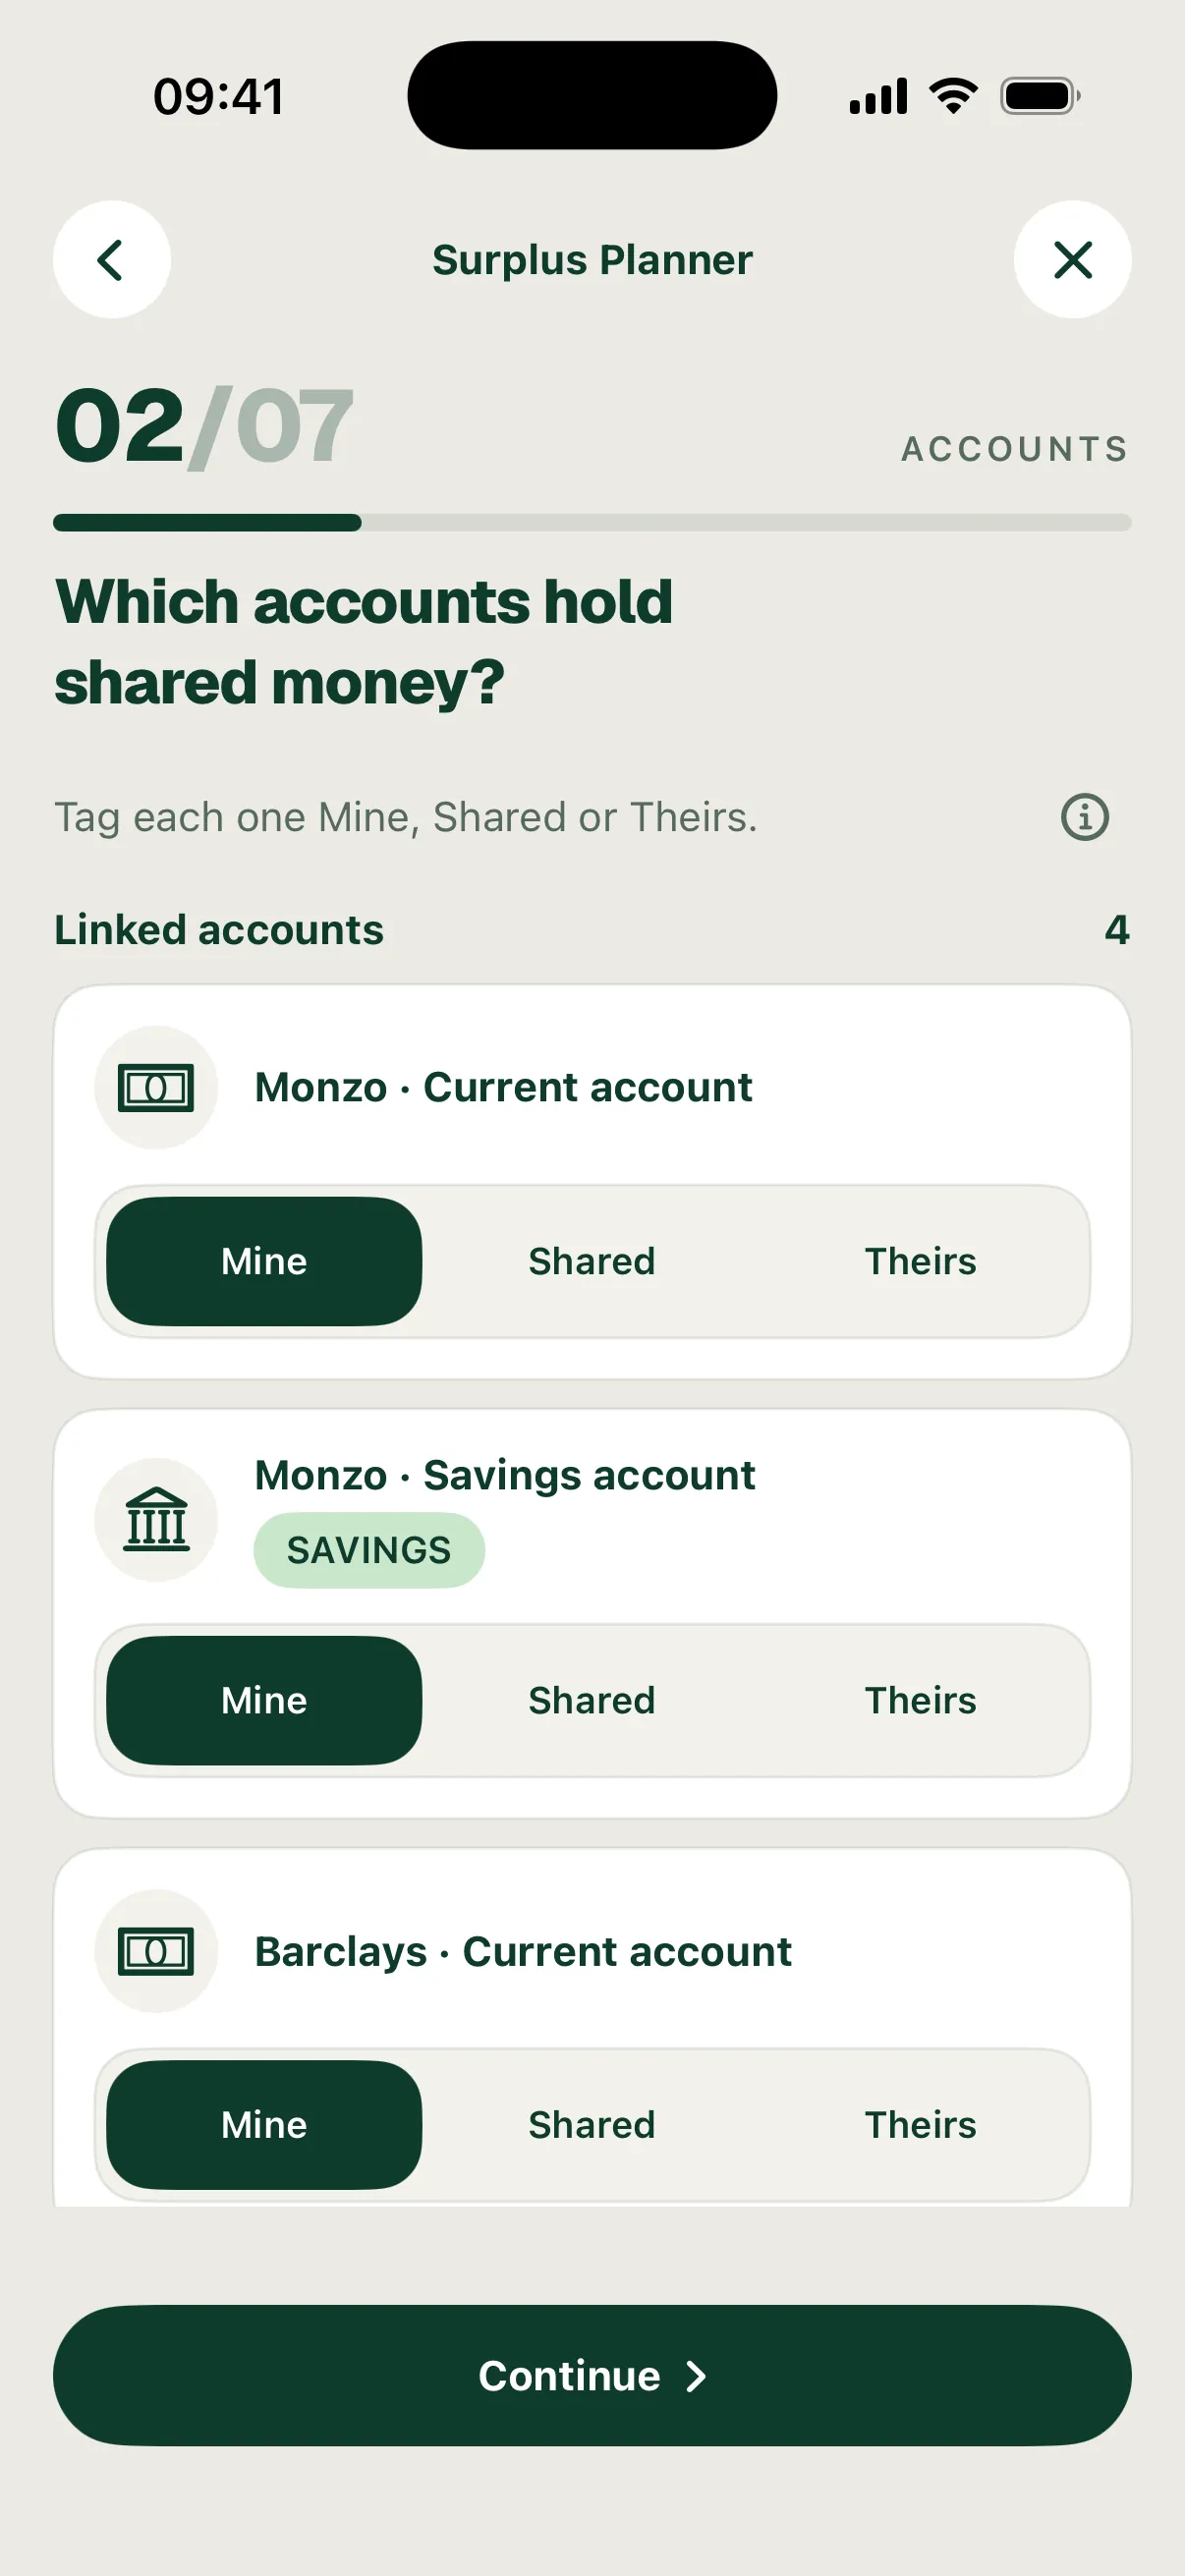
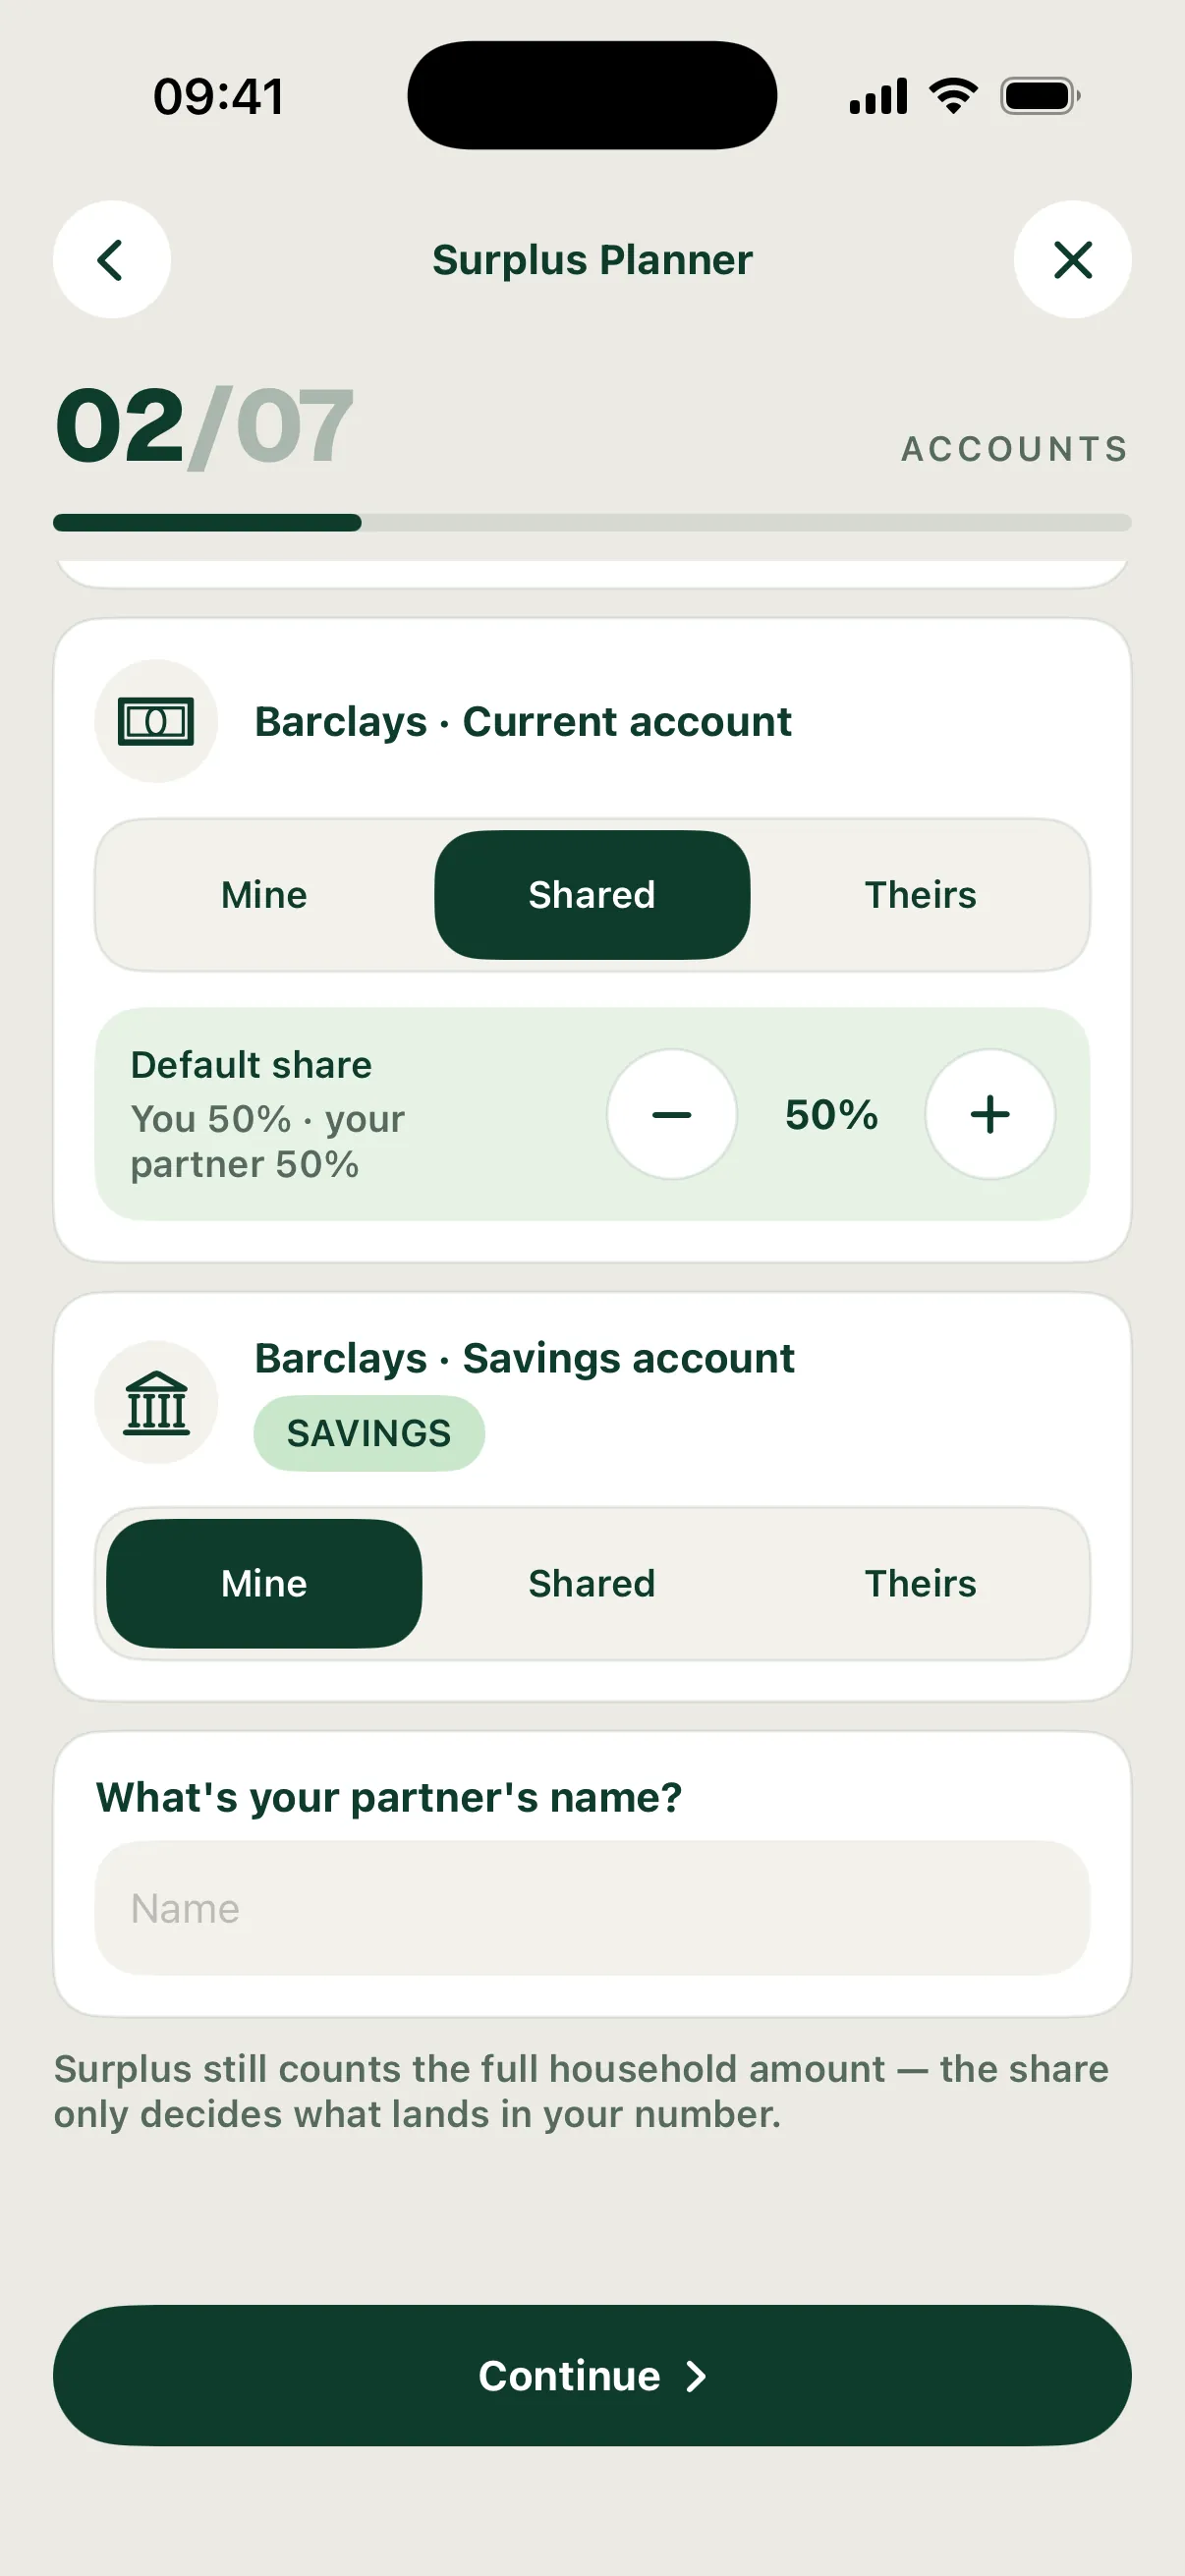
Every linked account is listed. Tag each one Mine, Shared or Theirs. Tag an account Shared if the income or spending in it belongs to both of you, like a joint account or the one your partner’s salary lands in. Anything tagged Mine is all yours and is never split. Theirs means nothing in that account lands in your number.
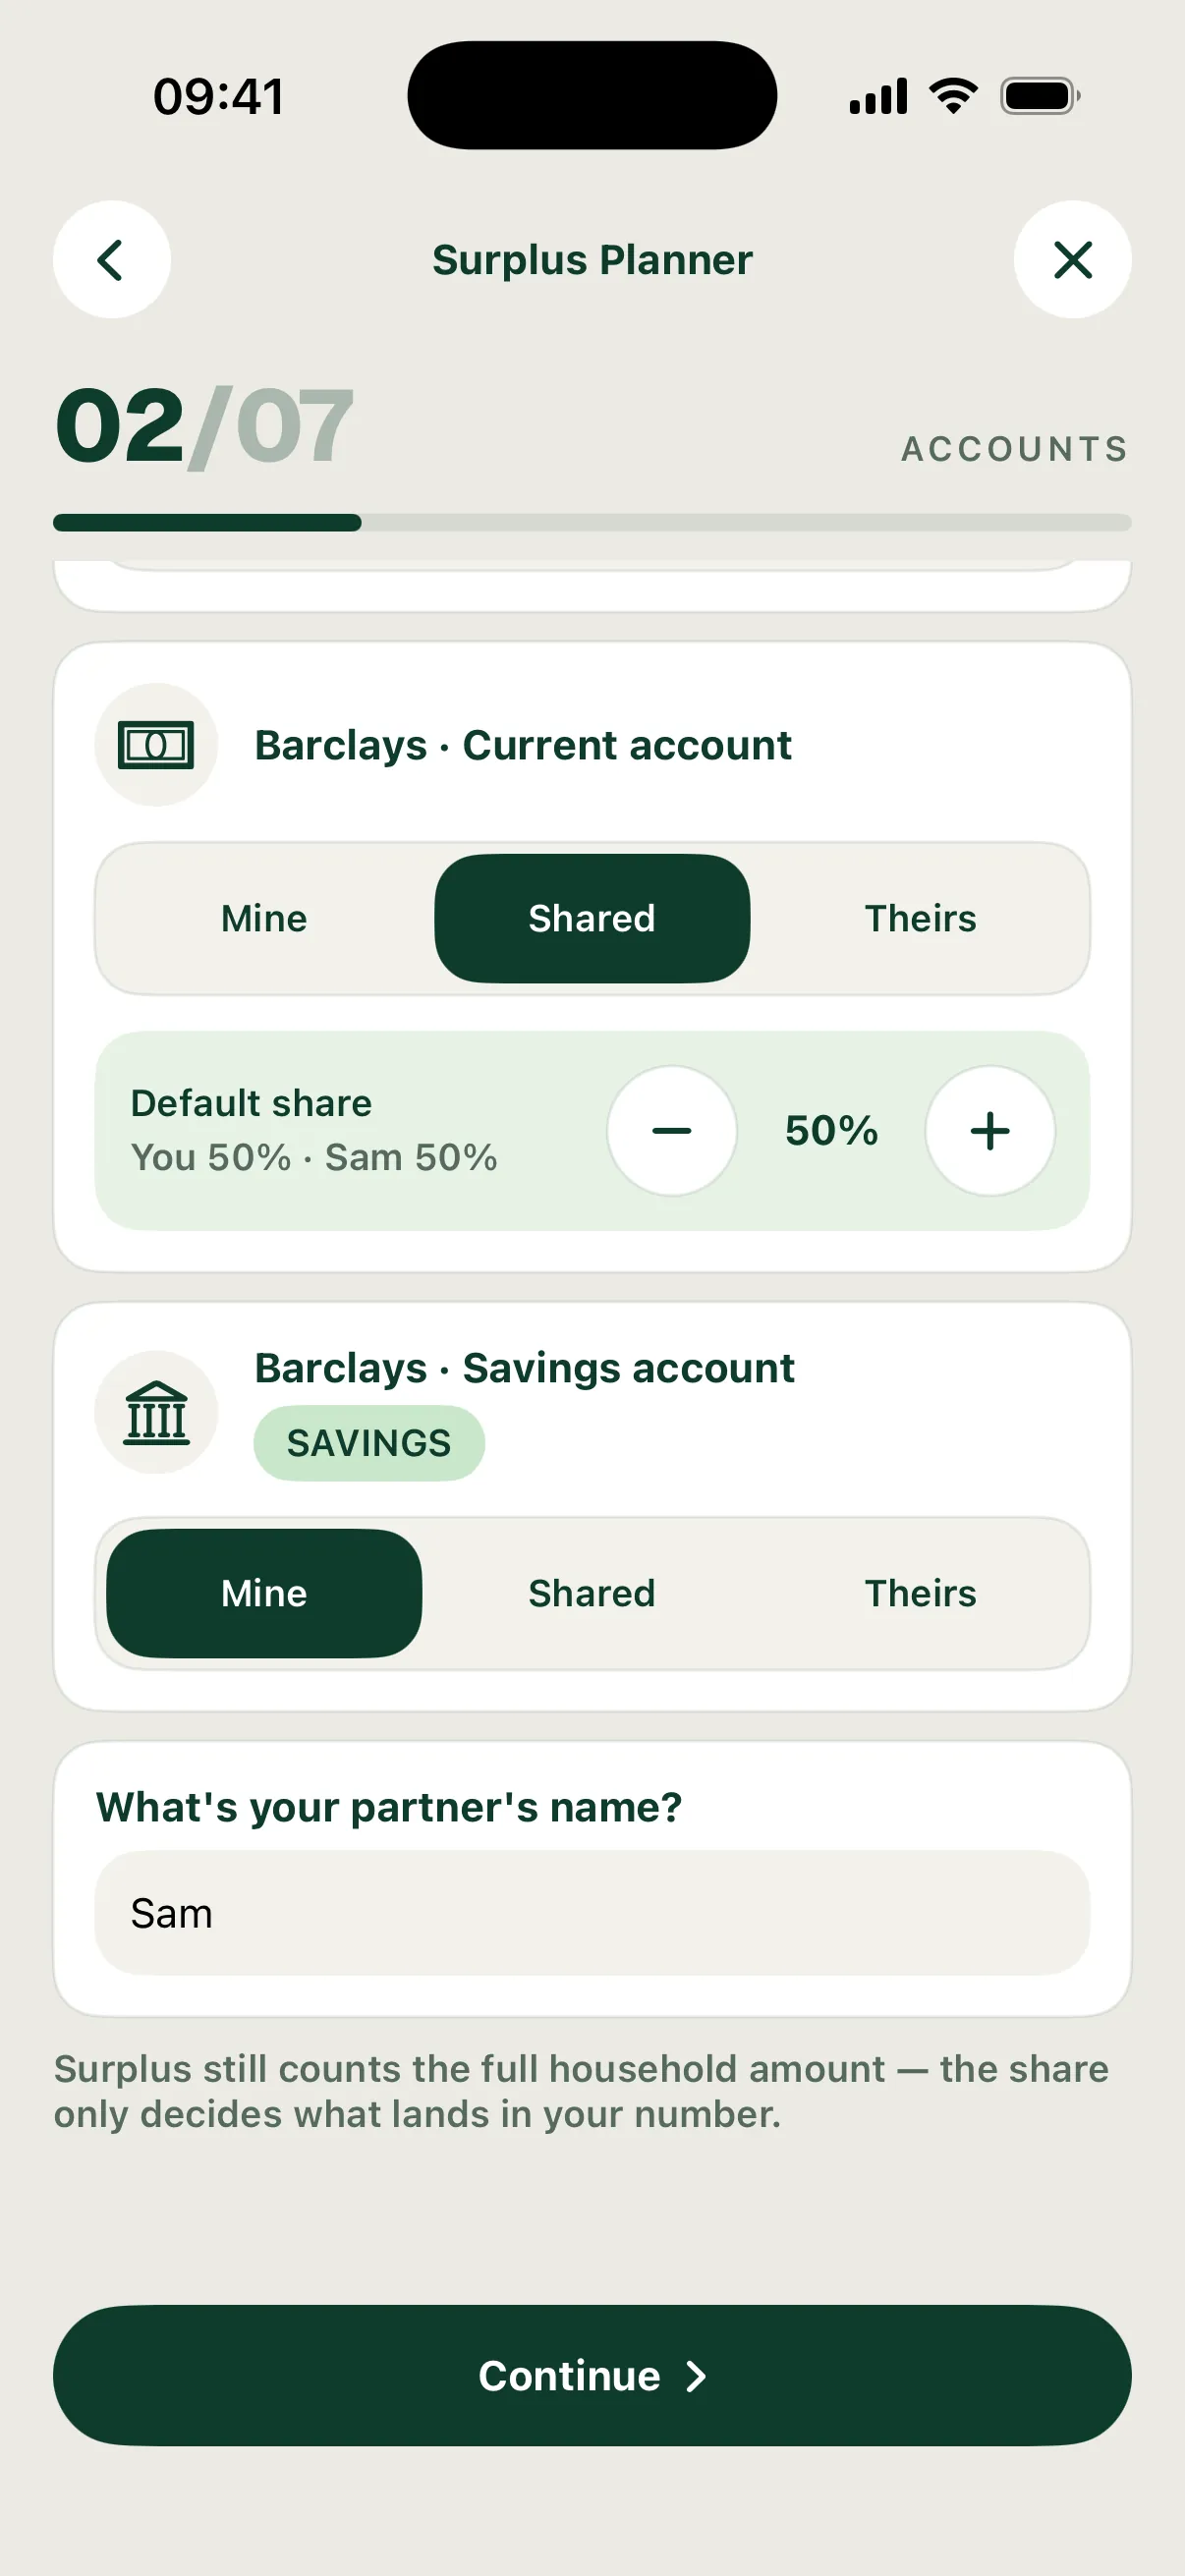
Tagging an account Shared shows a Default share stepper, starting at 50% each. This is the split applied to everything in that account unless you set a different share for a salary, bill or single purchase later. Enter your partner’s name at the bottom of the step. The default share then shows their name. Later steps offer it in place of Theirs.
In the example, the Barclays current account is tagged Shared and the partner is Sam, so the default share reads You 50% · Sam 50%. Both Monzo accounts and the Barclays savings account stay Mine.
Surplus still counts the full household amount. The share only decides what lands in your number. If you tag every account Mine but your partner’s money sits in accounts you haven’t linked, carry on and choose Some happens elsewhere on the next step.
Step 3: Coverage
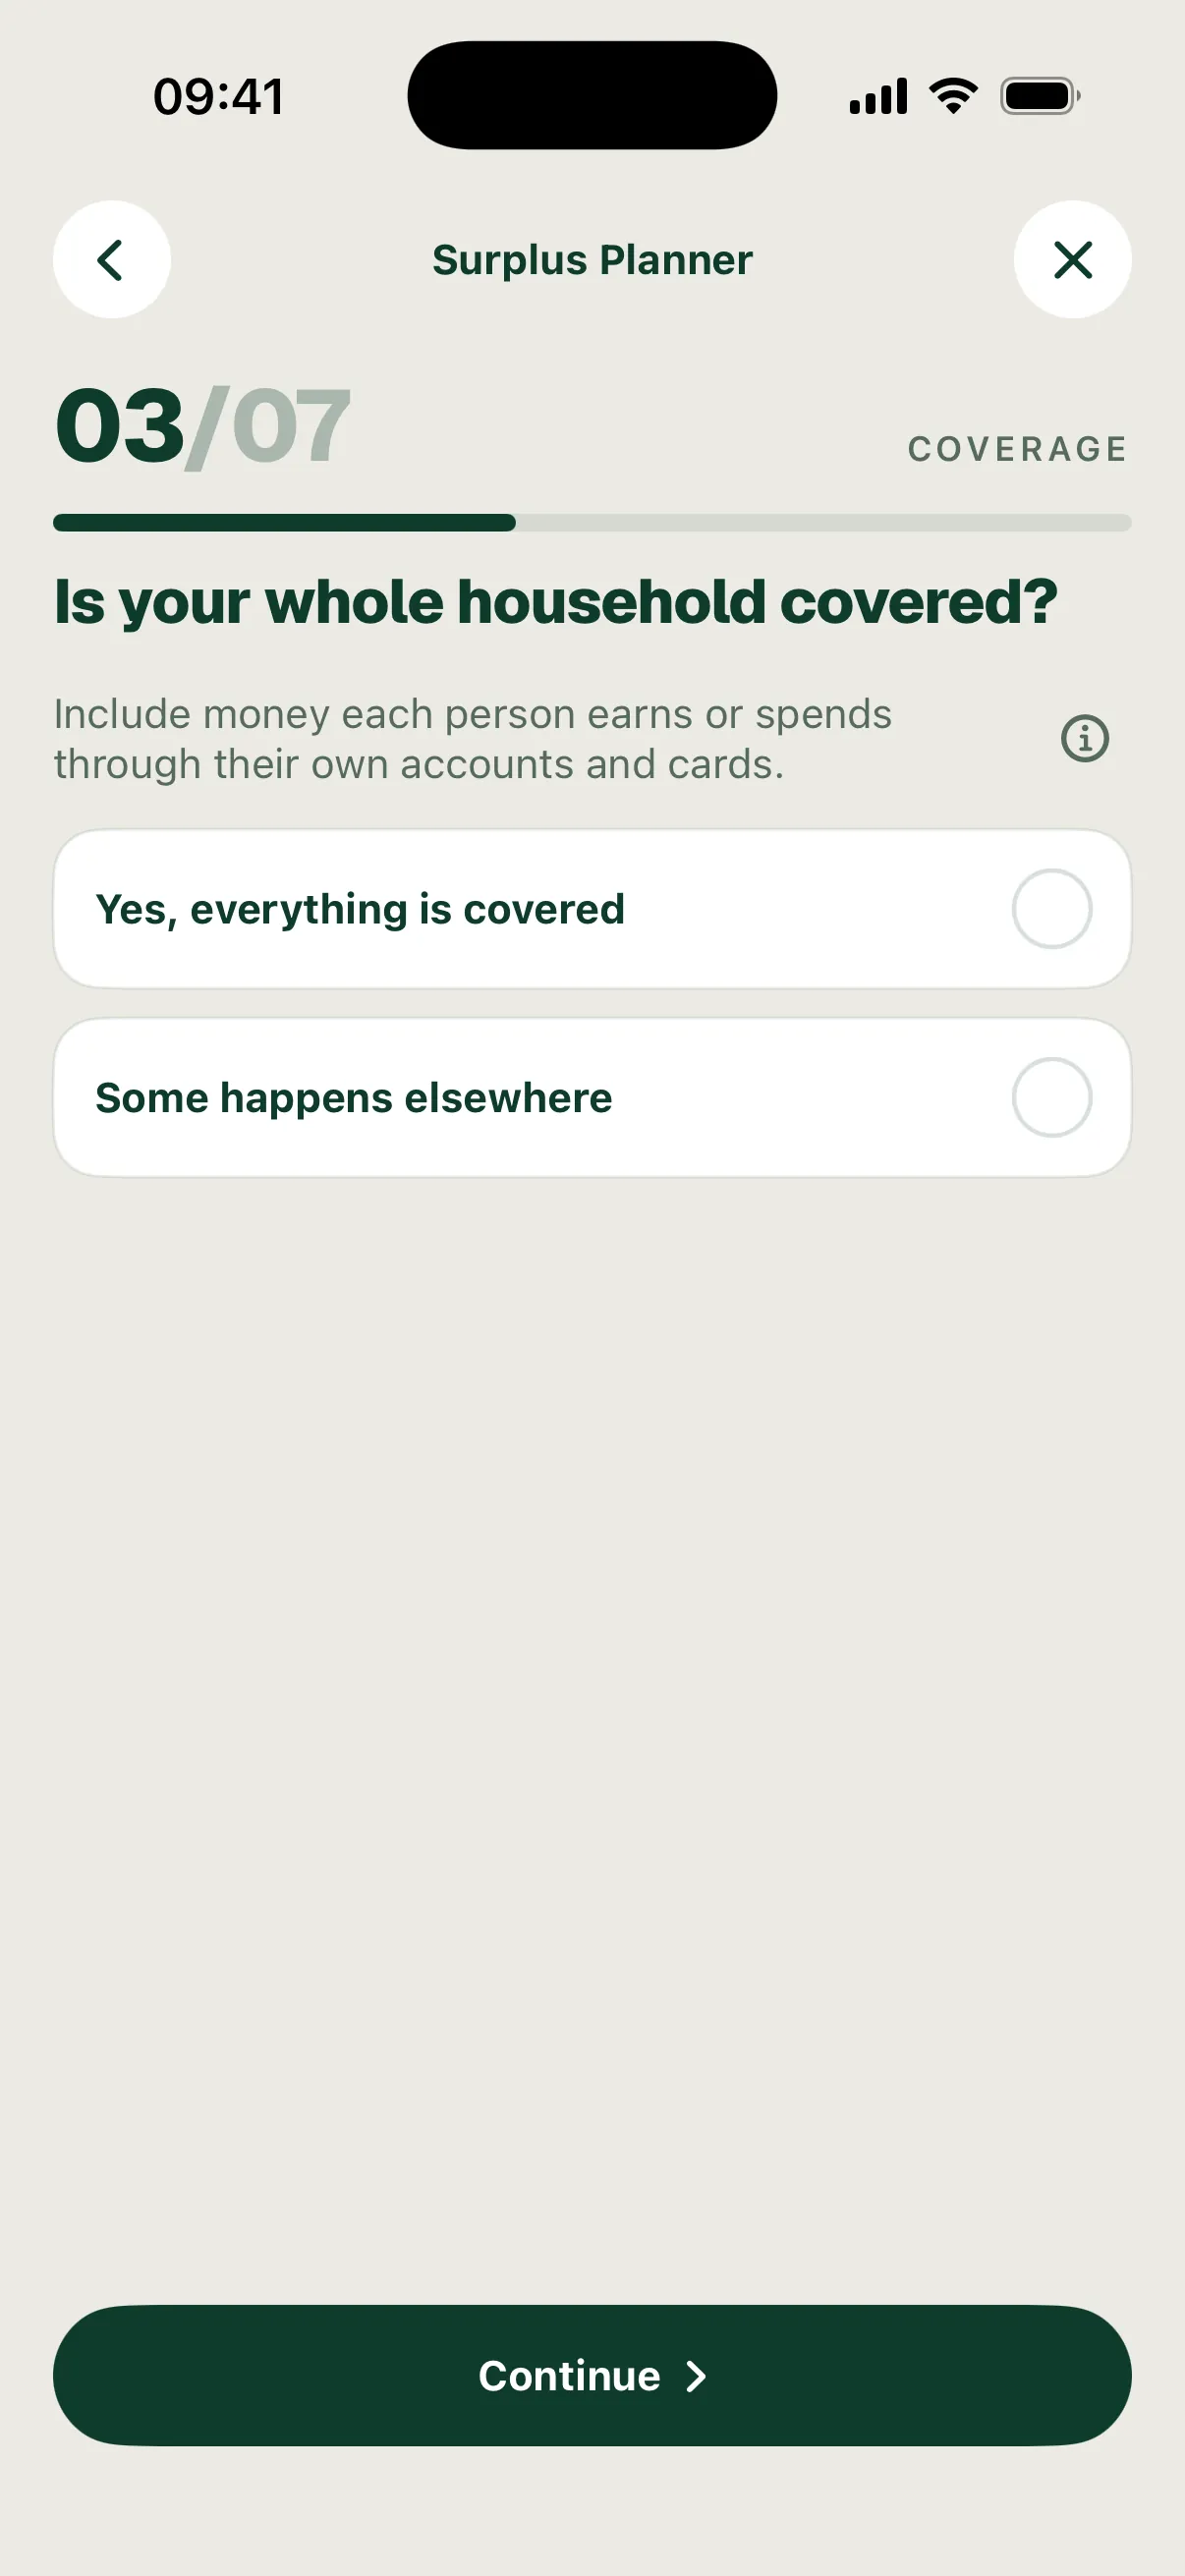
Check whether your linked accounts cover your whole household. Include money each person earns or spends through their own accounts and cards, not only the joint account.
- Yes, everything is covered: the linked accounts already hold all household income and spending. Nothing needs adding.
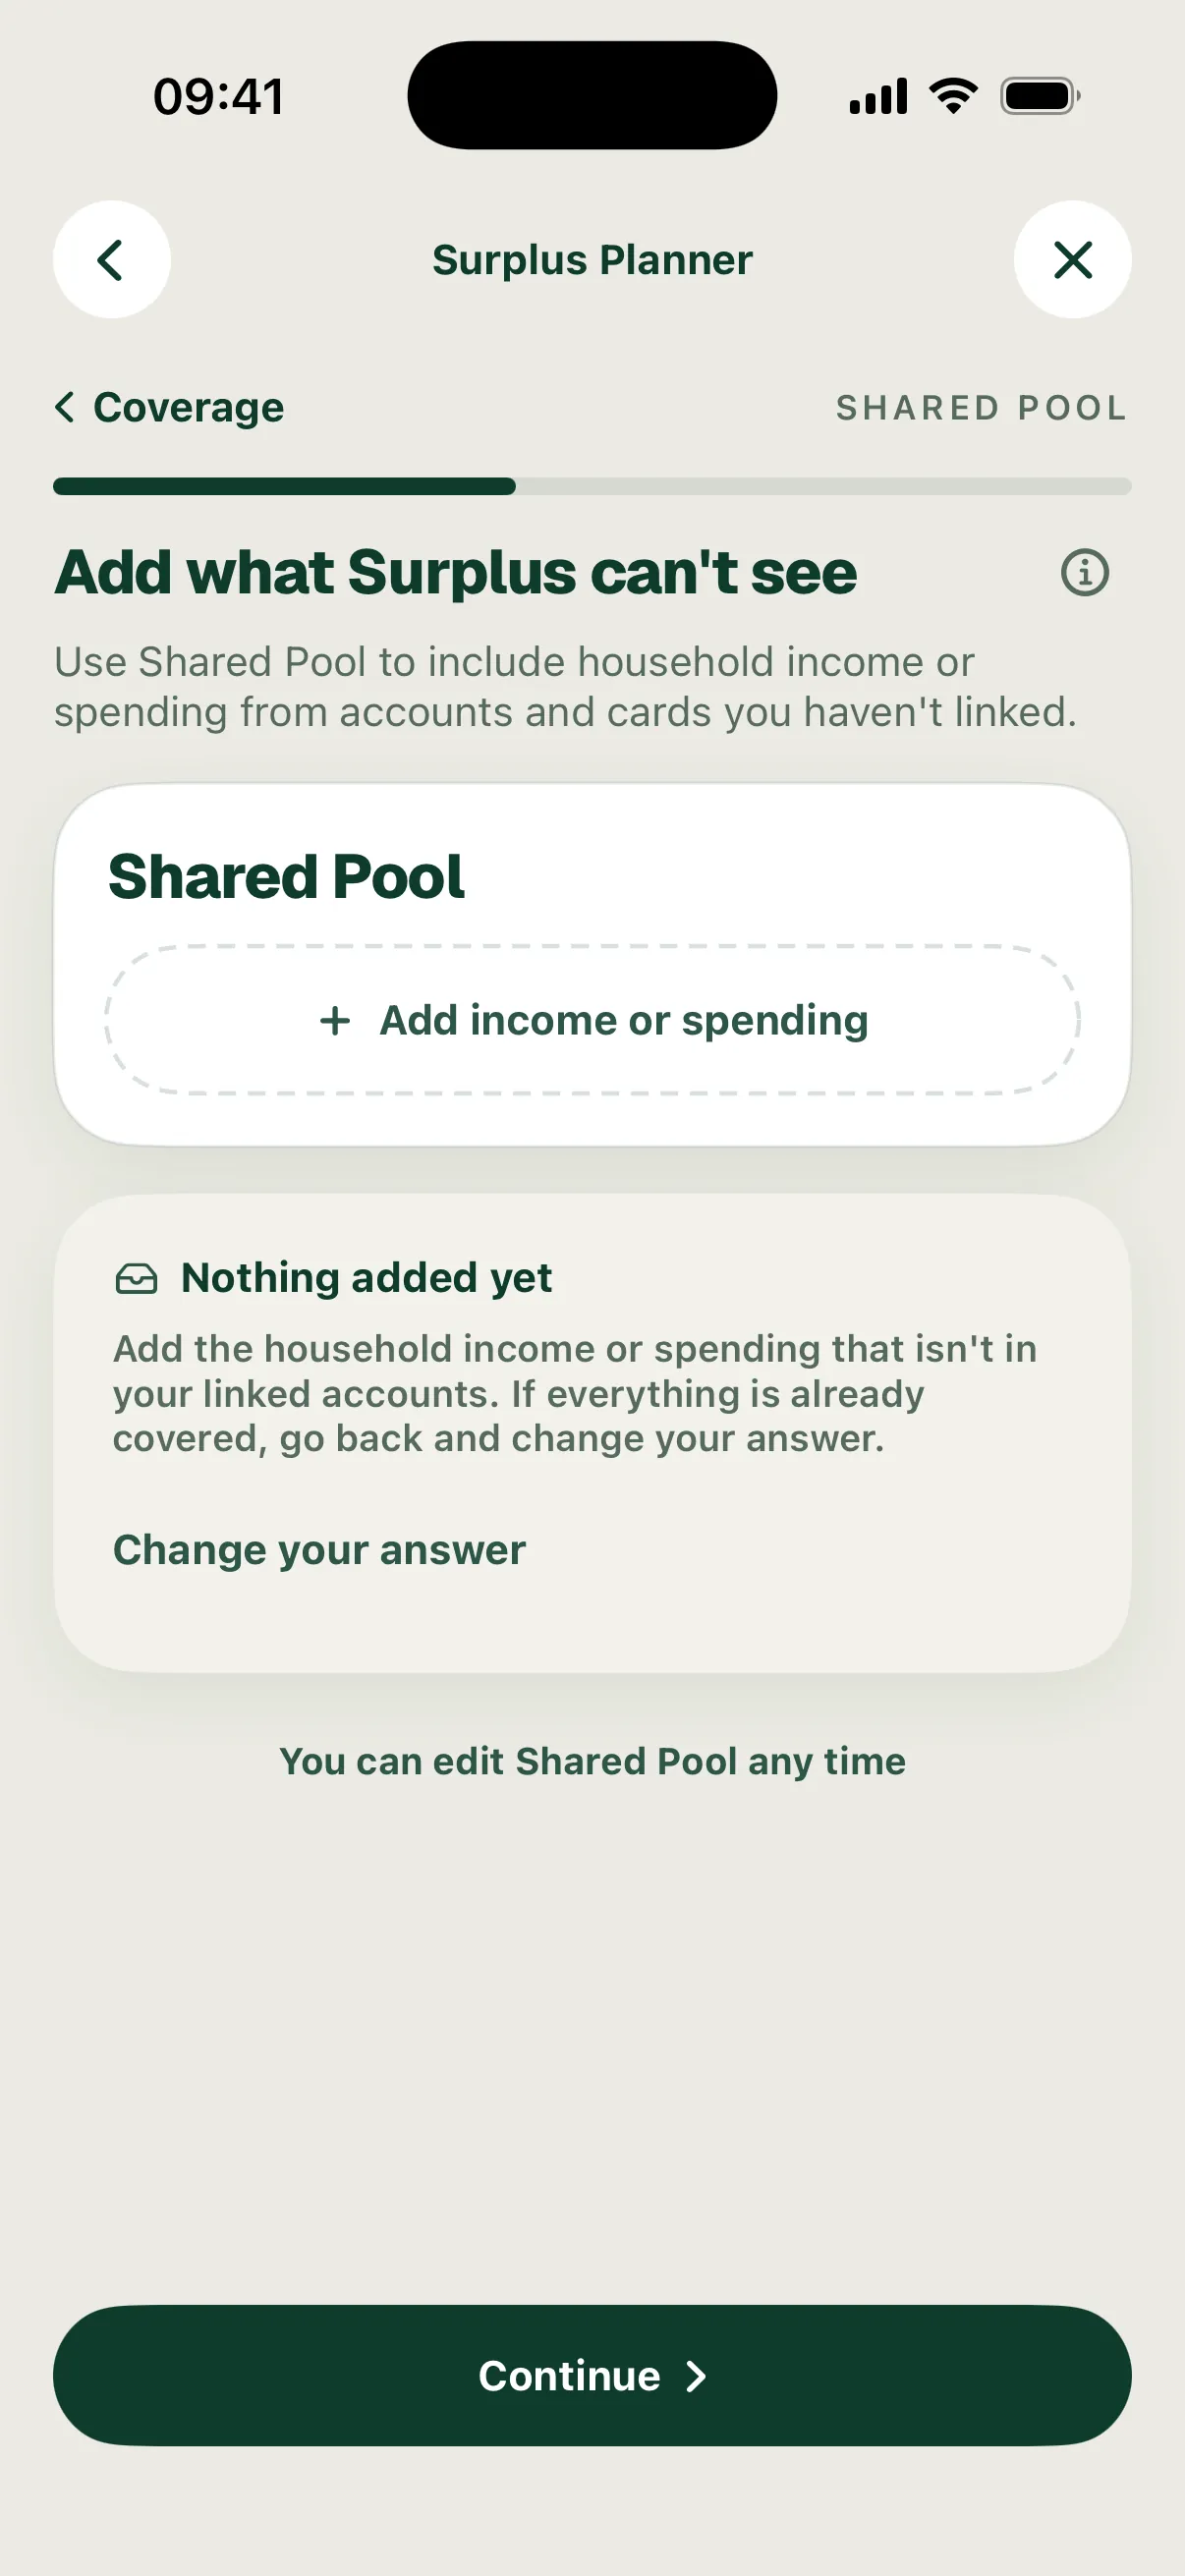
- Some happens elsewhere: add only the missing income or spending in Shared Pool. Estimates are fine.
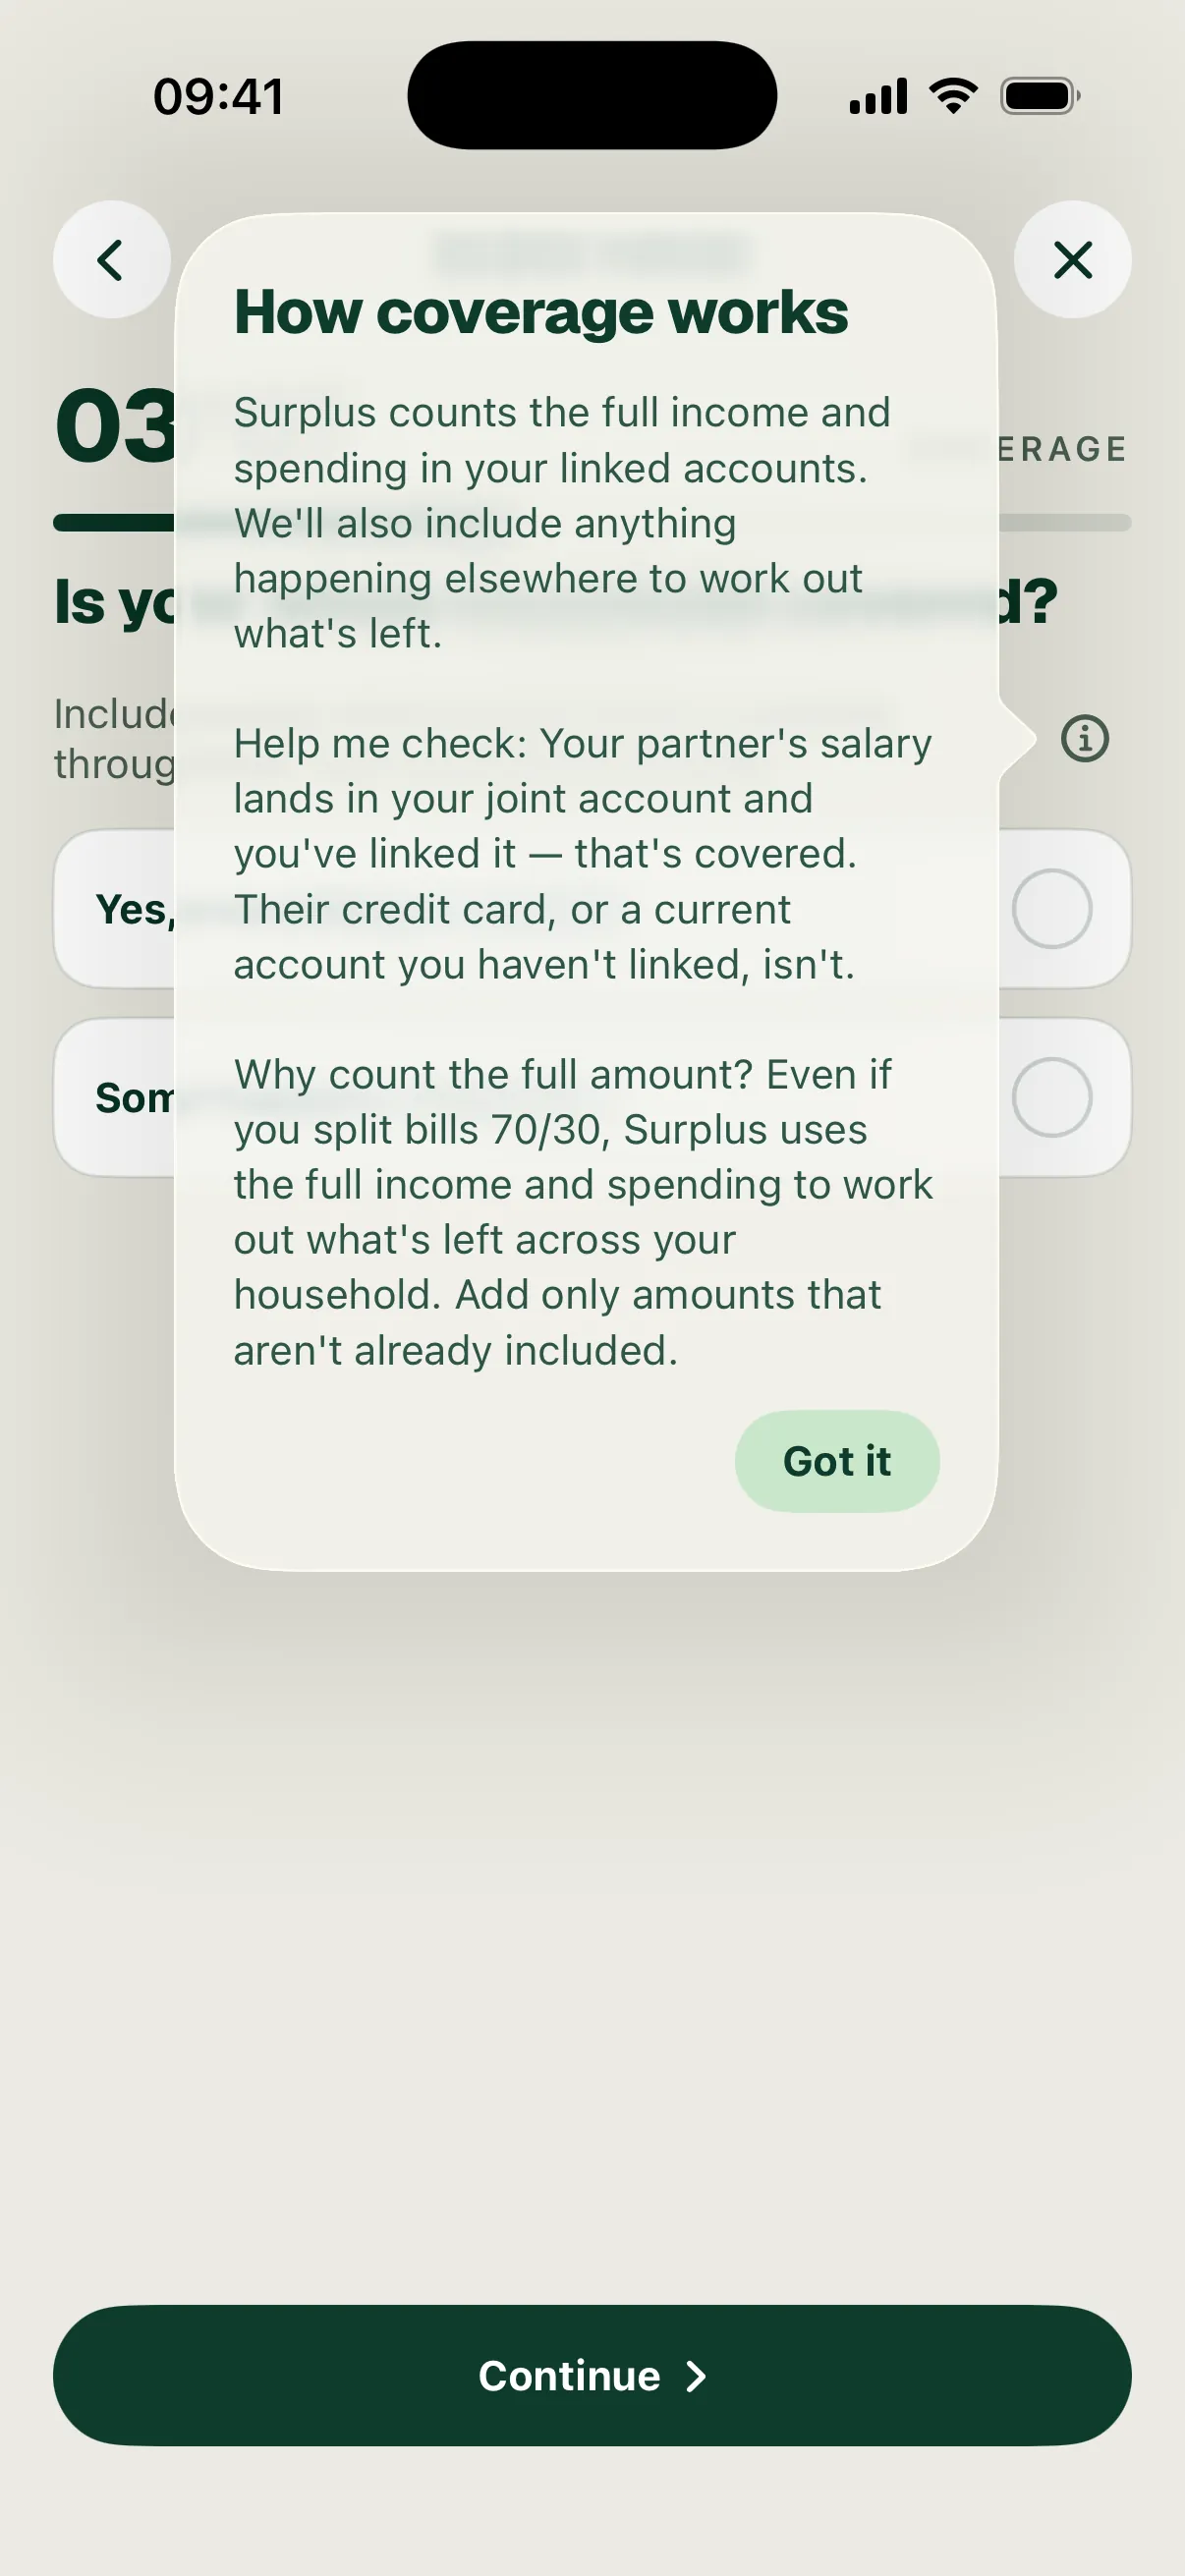
Use the How coverage works button for a worked check. A partner’s salary that lands in your linked joint account is already covered. Their credit card, or a current account you haven’t linked, is not. Even if you split bills 70/30, Surplus uses the full income and spending to work out what is left across the household, so add only amounts that are not already included.
Add missing income or spending in Shared Pool
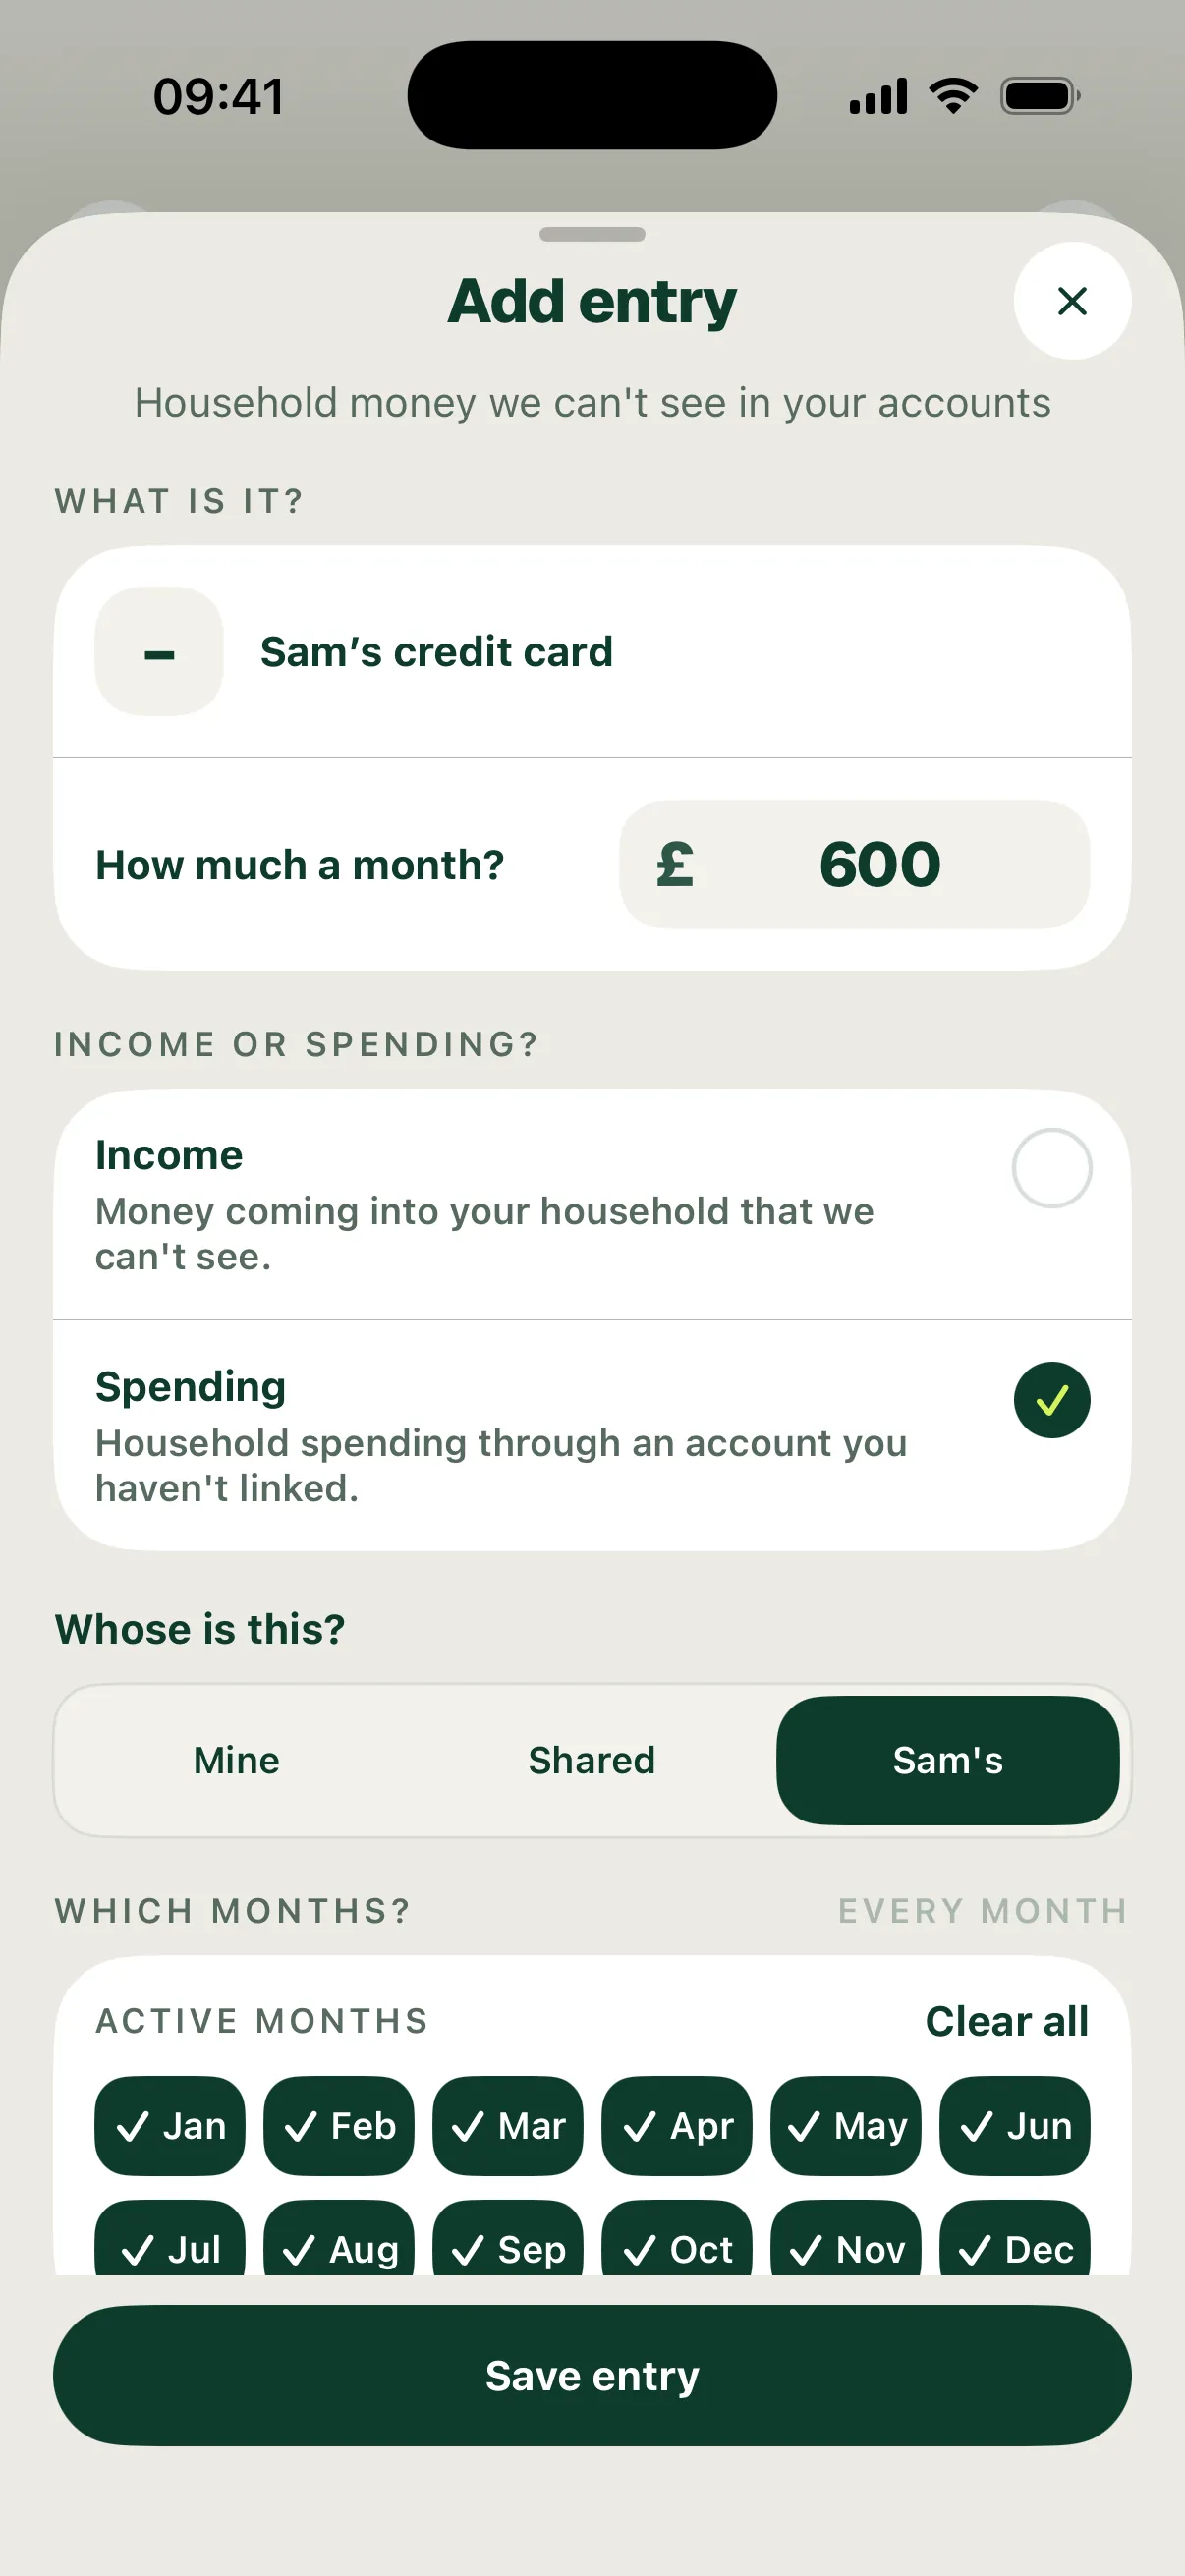
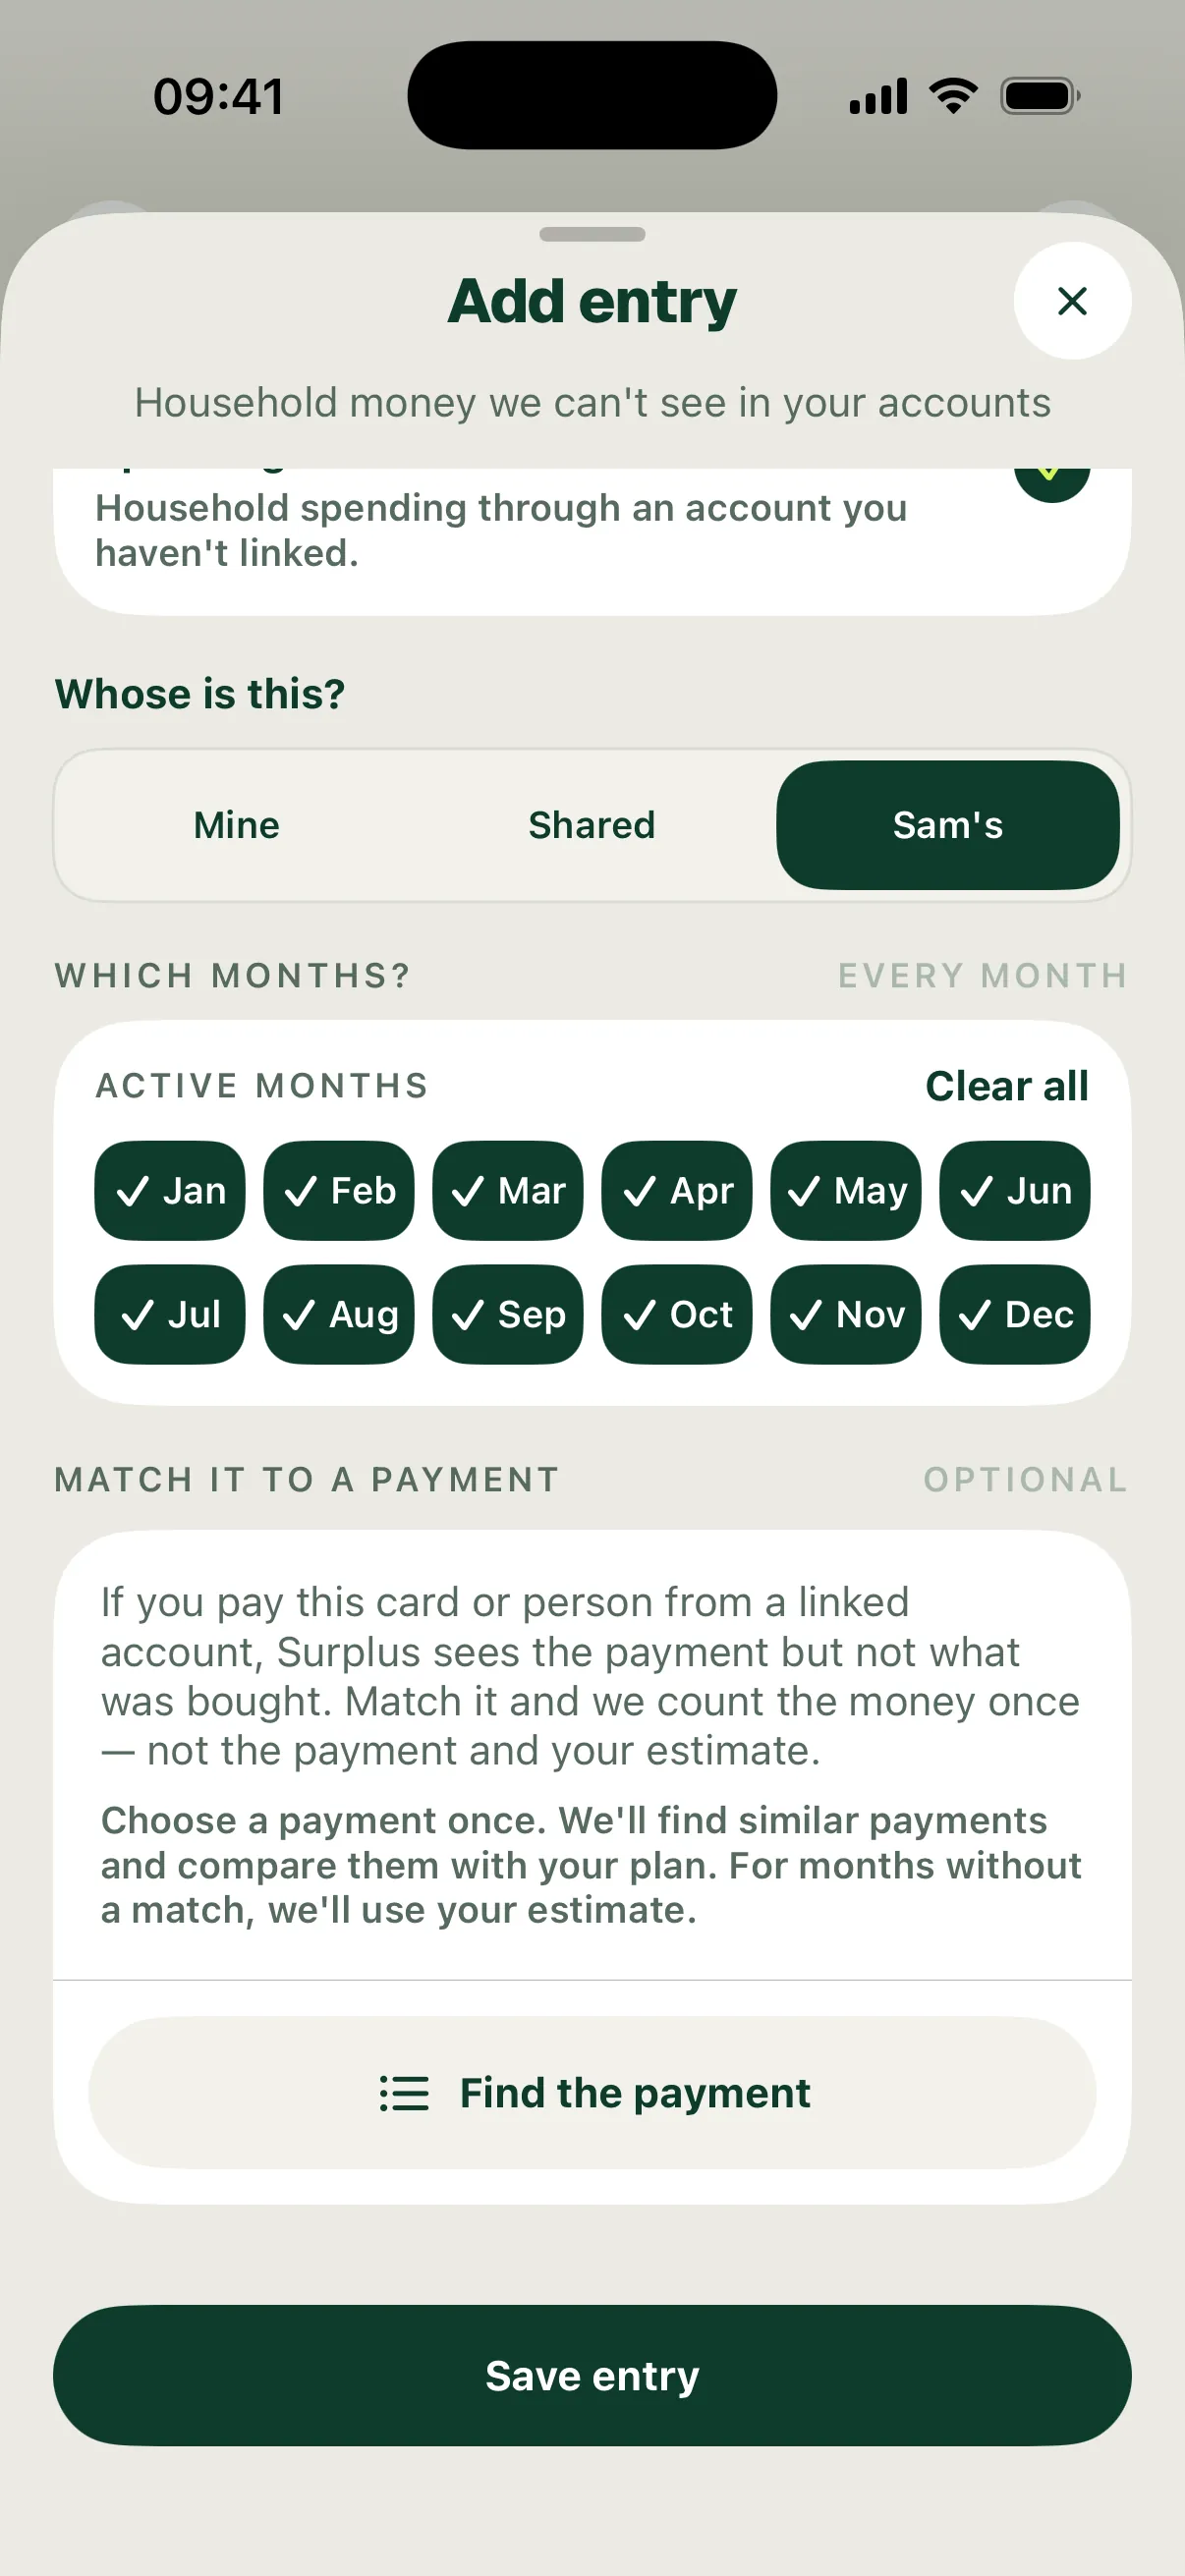
Choosing Some happens elsewhere opens Shared Pool. Choose Add income or spending, give the entry a recognisable name and enter its monthly amount. Select Income or Spending, then choose whose it is: Mine, Shared or your partner’s. Select the active months and review the schedule summary before saving the entry.
Income adds money missing from the linked household picture. Spending subtracts household expenditure that happens elsewhere. A transfer between accounts you own does not create new household income.
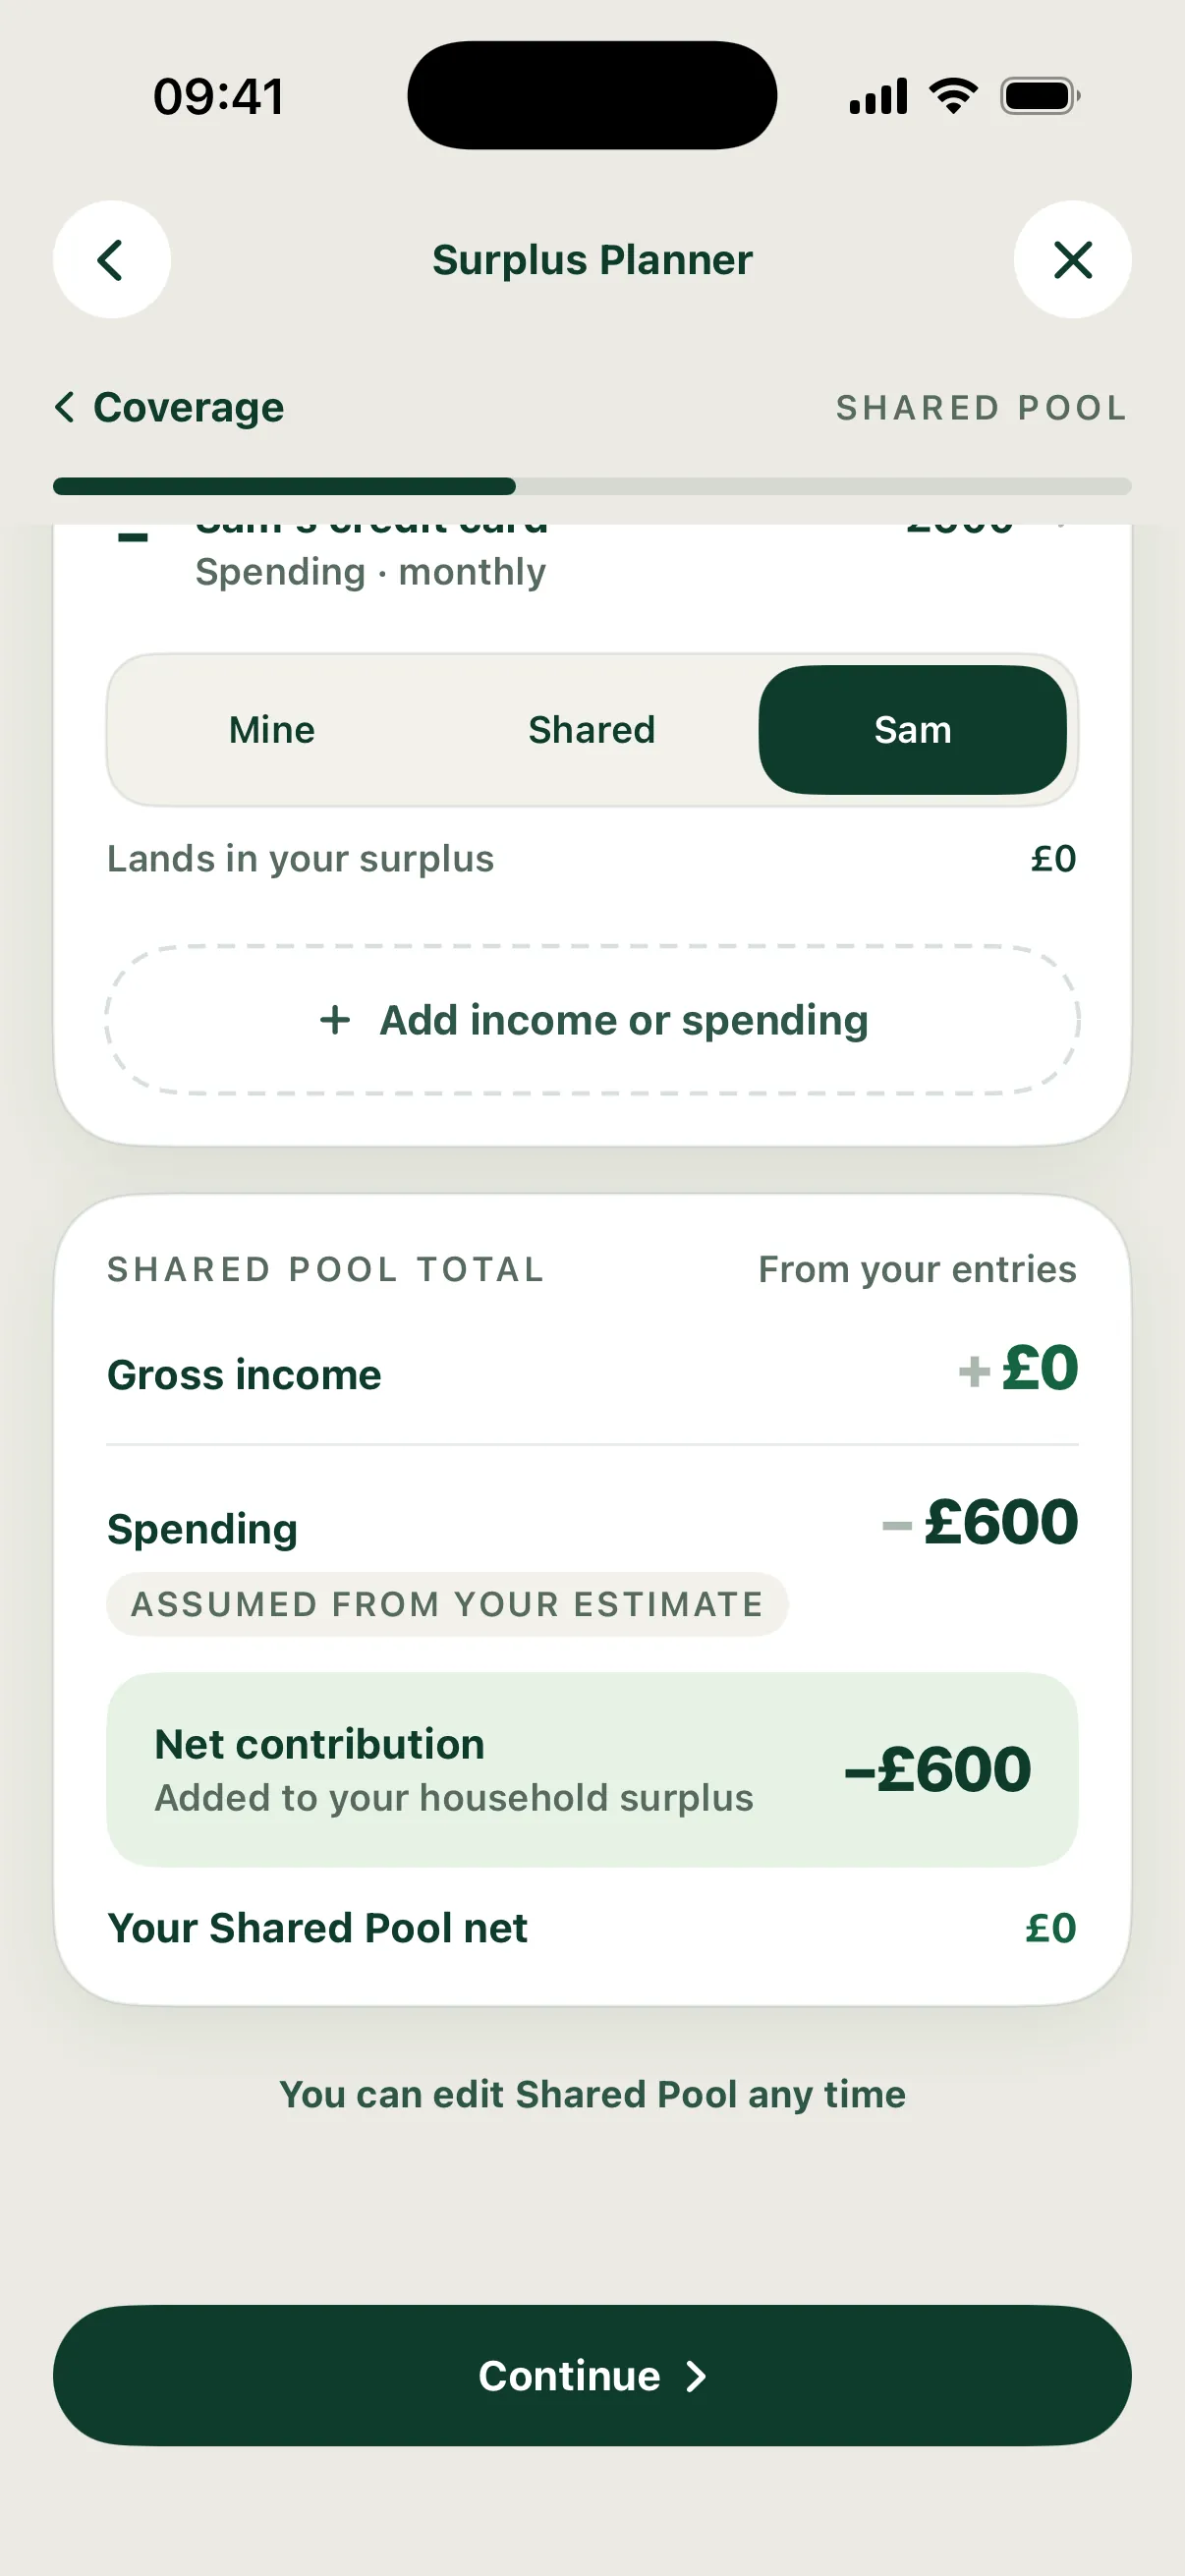
The example adds Sam’s credit card, £600 of spending a month, in every month. Because it is Sam’s, the entry shows Lands in your surplus £0. The Shared Pool total then reads spending minus £600, a net contribution of -£600 to the household surplus and Your Shared Pool net £0. Until Surplus can see a matching payment, an entry is labelled Assumed from your estimate.
A saved entry keeps its direction. Stop it and add a new entry if it should switch between income and spending. Matching it to a payment is optional: search for a related payment in a linked account, such as the monthly repayment to that card. Surplus can then use the real payments instead of the estimate for the months it finds them. The money is counted once.
Step 4: Income
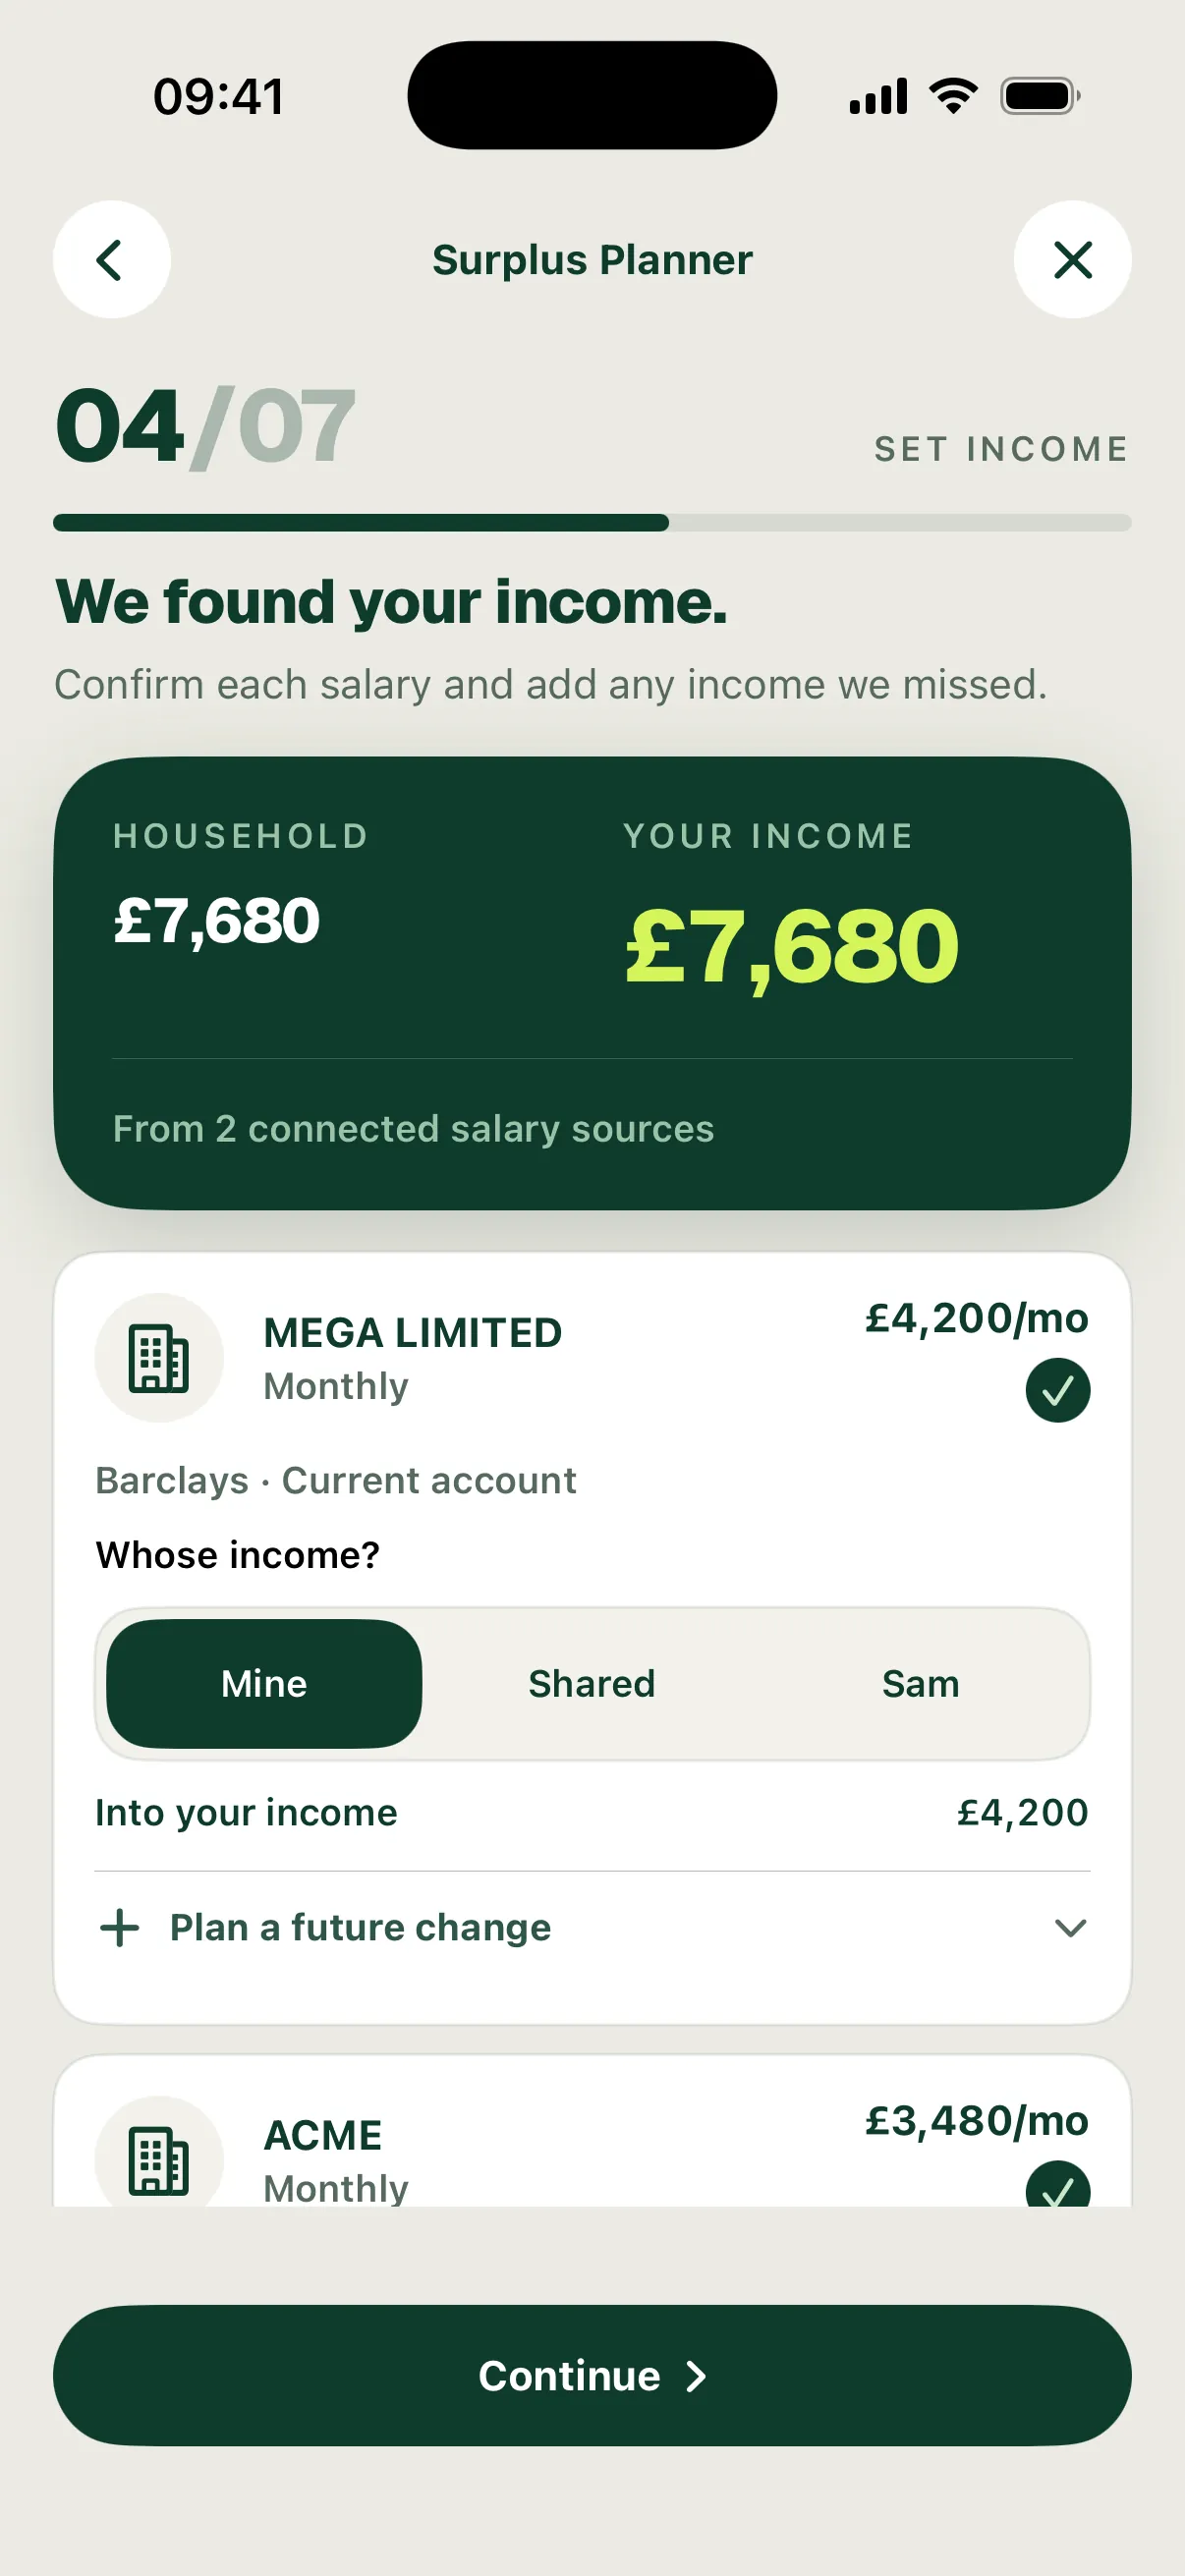
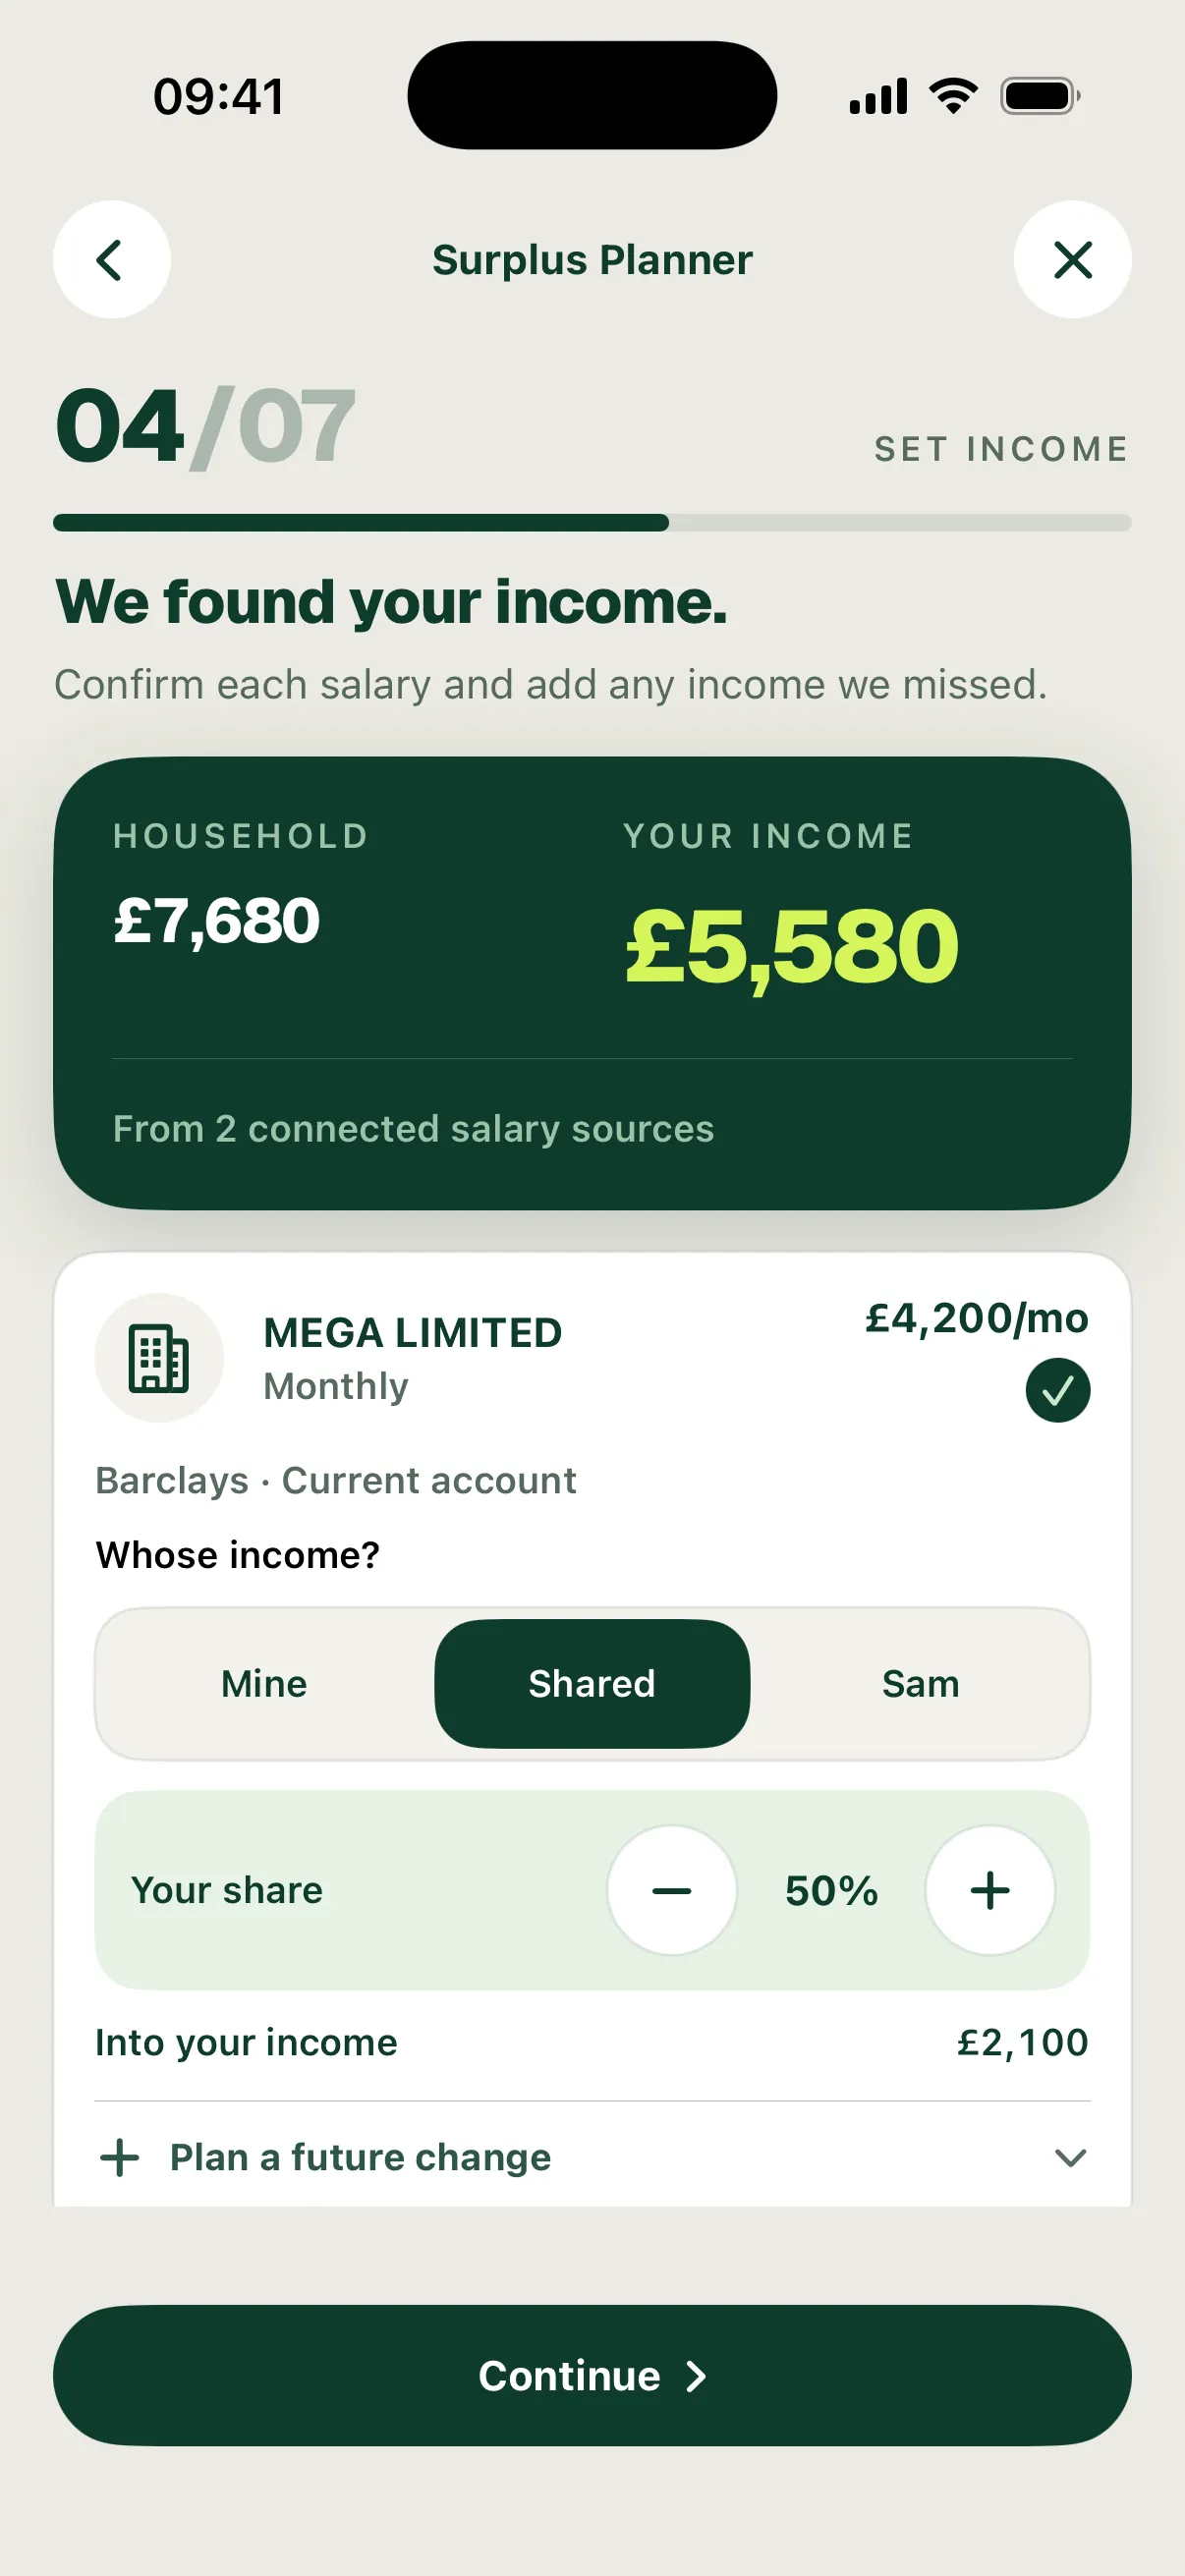
Check the detected salary sources and the projected monthly total. The header shows the household income beside your income. For a salary paid into a shared account, answer Whose income? with Mine, Shared or your partner’s name. Shared shows a Your share stepper and the Into your income line follows it. A salary in an account tagged Mine is marked Yours · set by this account.
In the example, the £4,200 MEGA LIMITED salary in the Barclays joint account is tagged Shared at 50%, so £2,100 goes into your income and your income becomes £5,580 of the household’s £7,680. Tagging the same salary as Sam’s puts £0 into your income and leaves your income at £3,480 from ACME.
Use Plan a future change for a planned change, or Add income stream for income missing from this part of your plan. Do not add the same income in both this step and Shared Pool.
Step 5: Bills
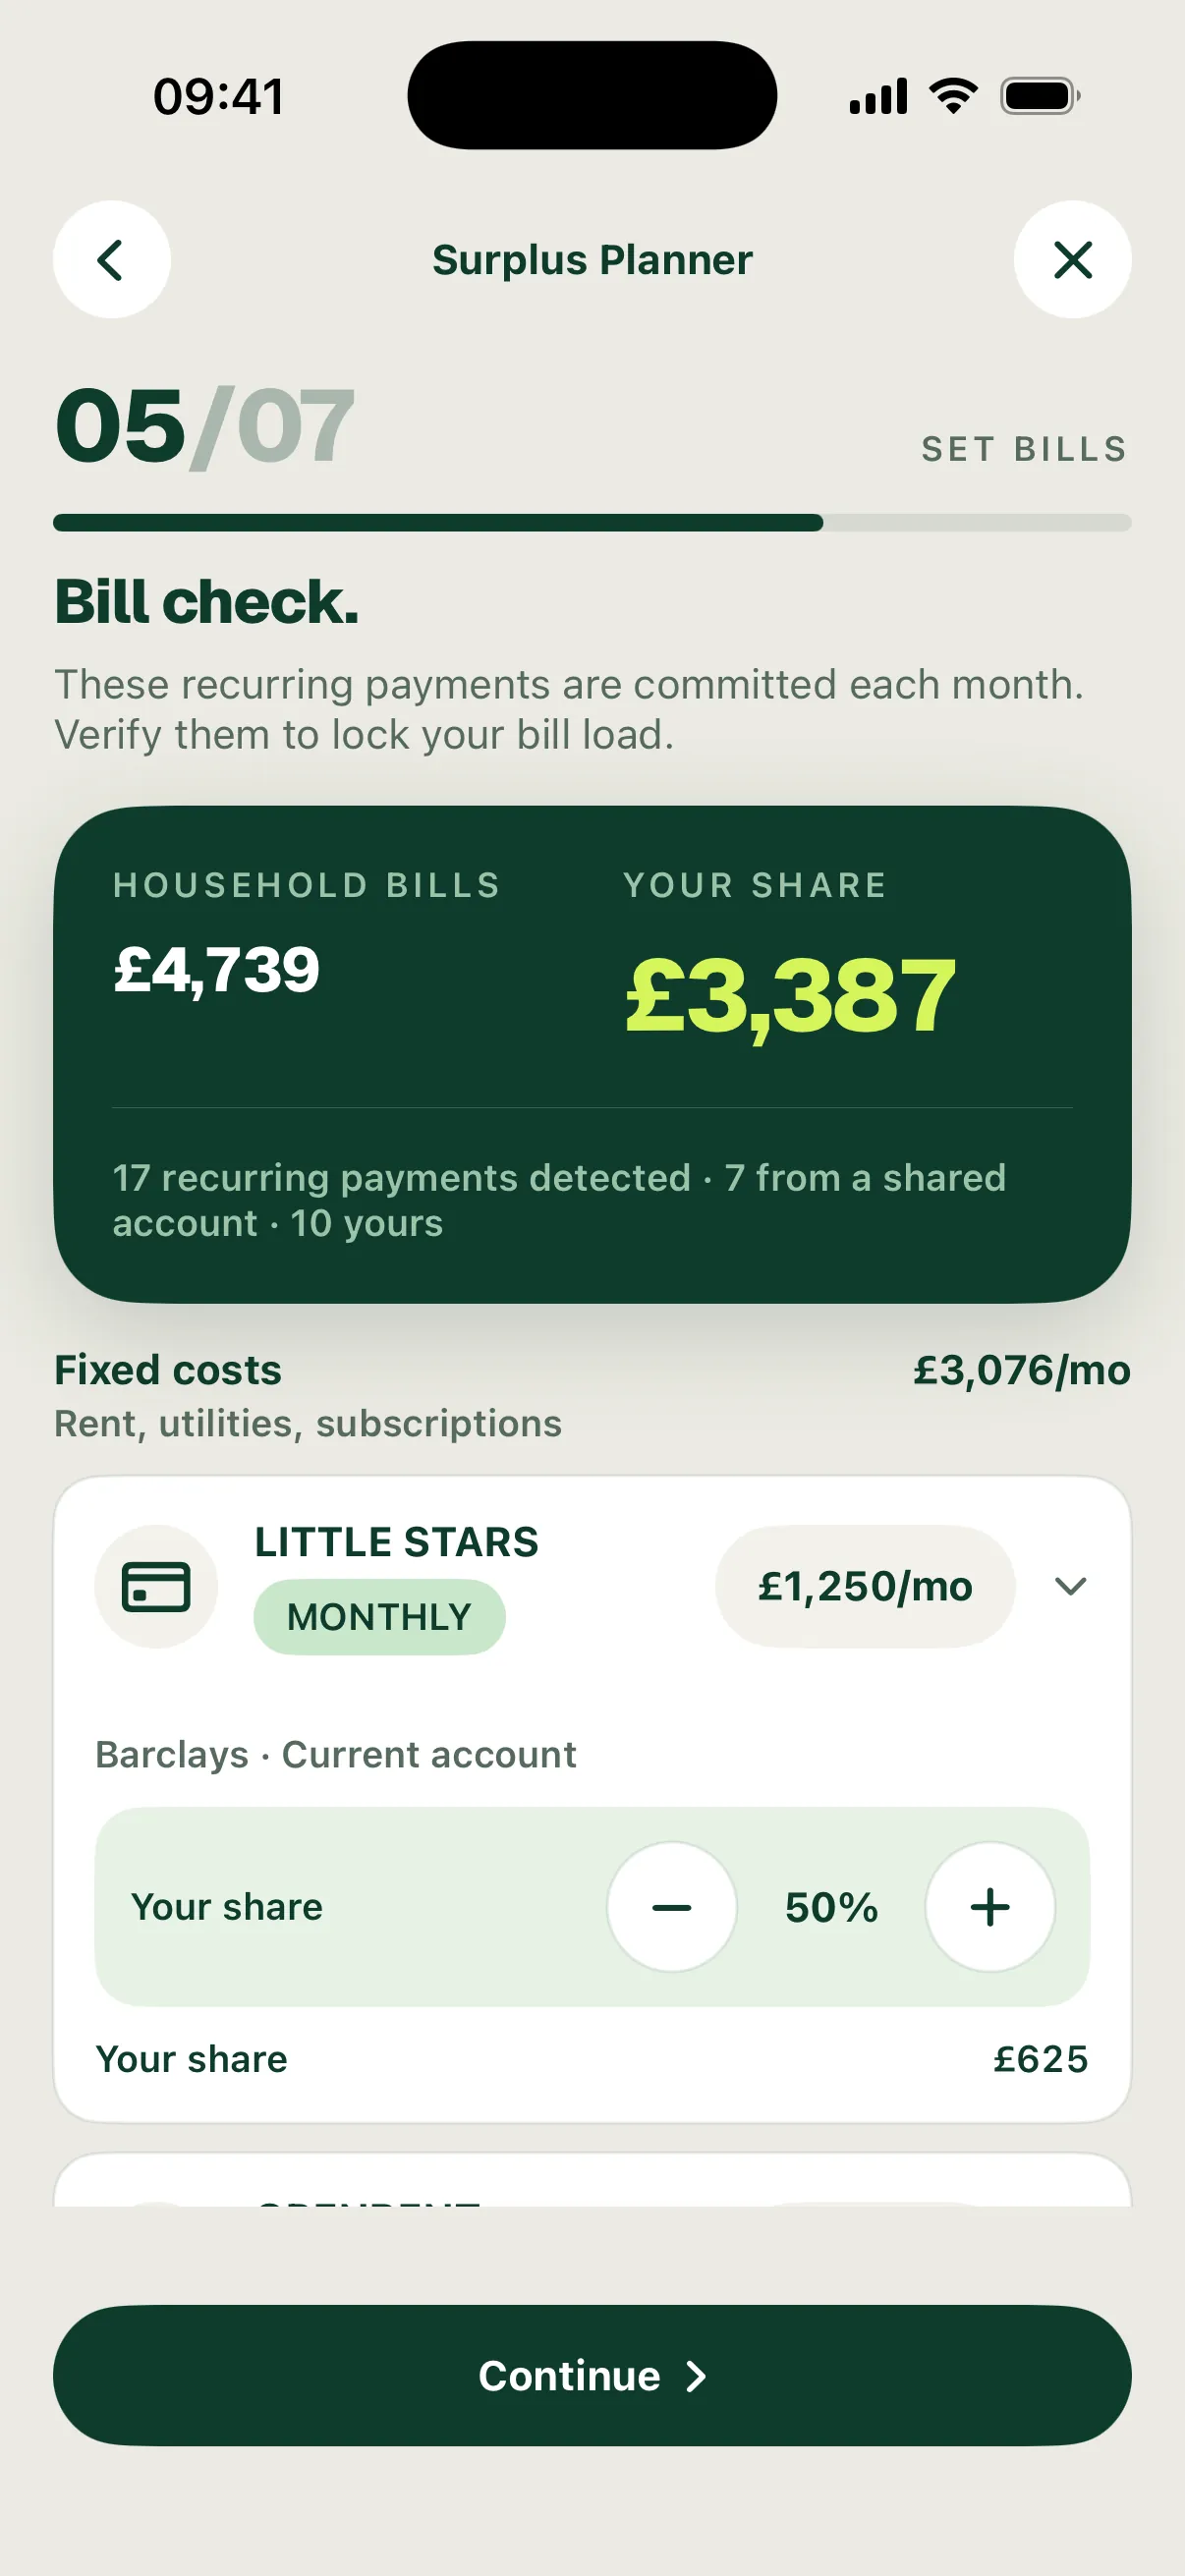
Review recurring payments and essential spending. The header compares household bills with your share. The line under it says how many payments come from a shared account. Expand a bill to check its monthly amount and active months. Add a missing bill where needed.
A bill paid from a shared account gets its own Your share stepper, starting at the account’s default share. In the example, the £1,250 nursery bill from the Barclays joint account is split 50%, so £625 is yours, while the £750 rent from the Monzo account is Yours · set by this account. Household bills come to £4,739 and your share to £3,387.
Essential spending includes variable must-haves such as groceries and transport, so the setup’s total bill load can be higher than the separate recurring-bills list.
Step 6: Discretionary
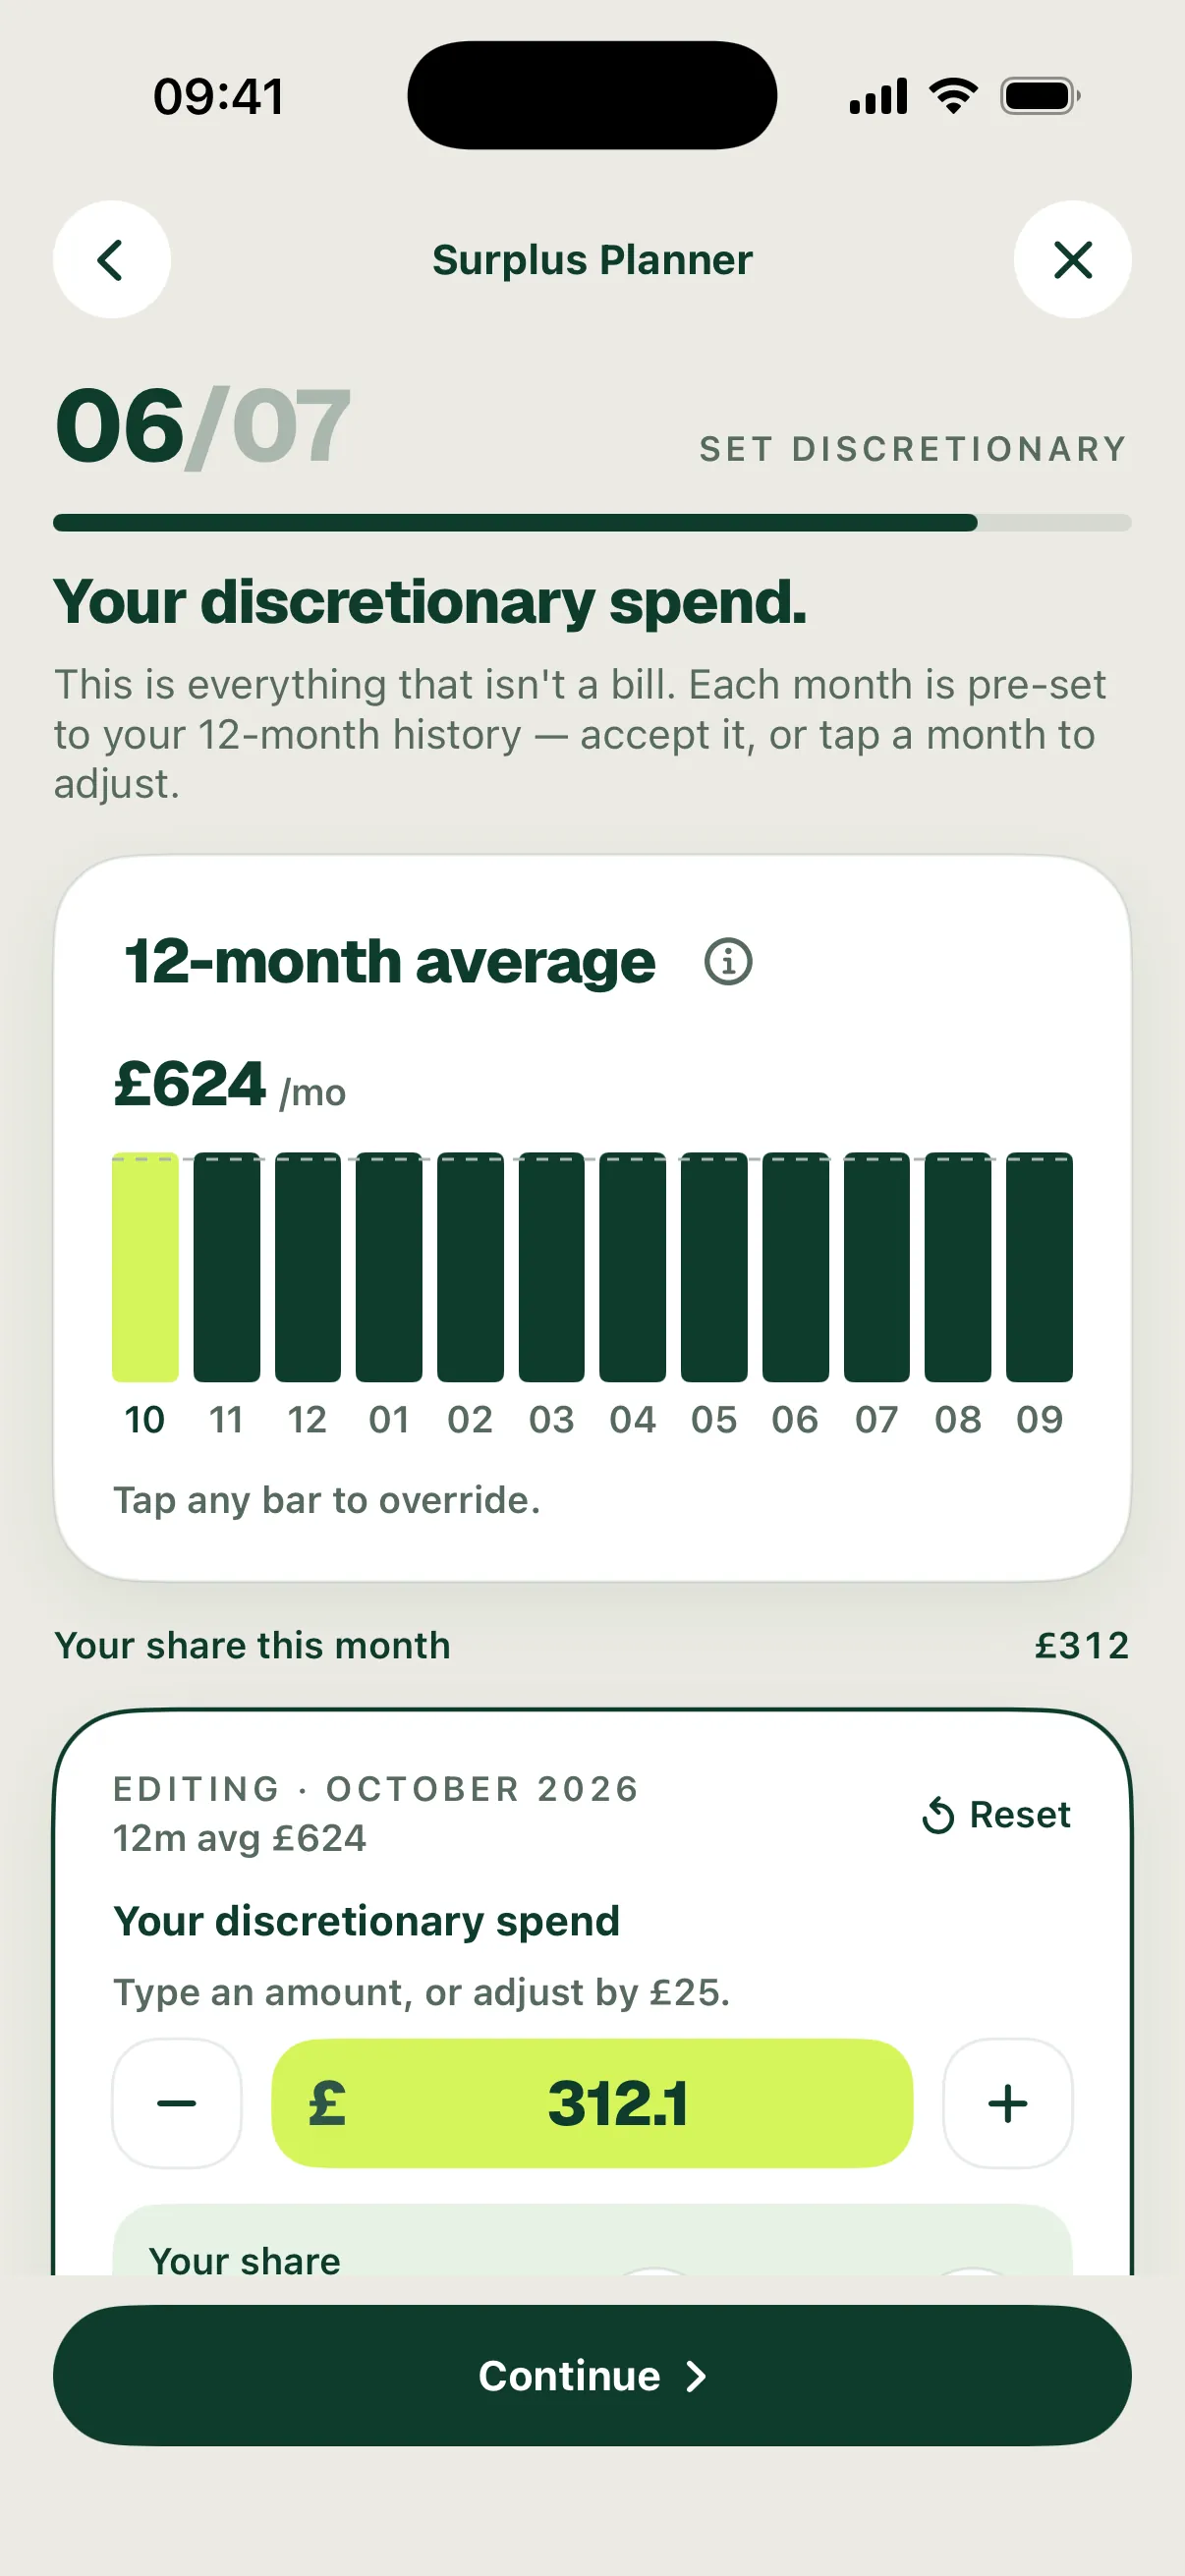
Review the monthly discretionary amounts based on your 12-month history. The chart shows the household’s typical month as a dashed line. Tap any month to override that month’s amount, or apply one amount to all months. Reset restores the starting value for the selected month. Your share this month shows the part of the discretionary spend that counts towards your number.
The example keeps the £624 household average in every month, of which £312 is your share.
Step 7: Your surplus
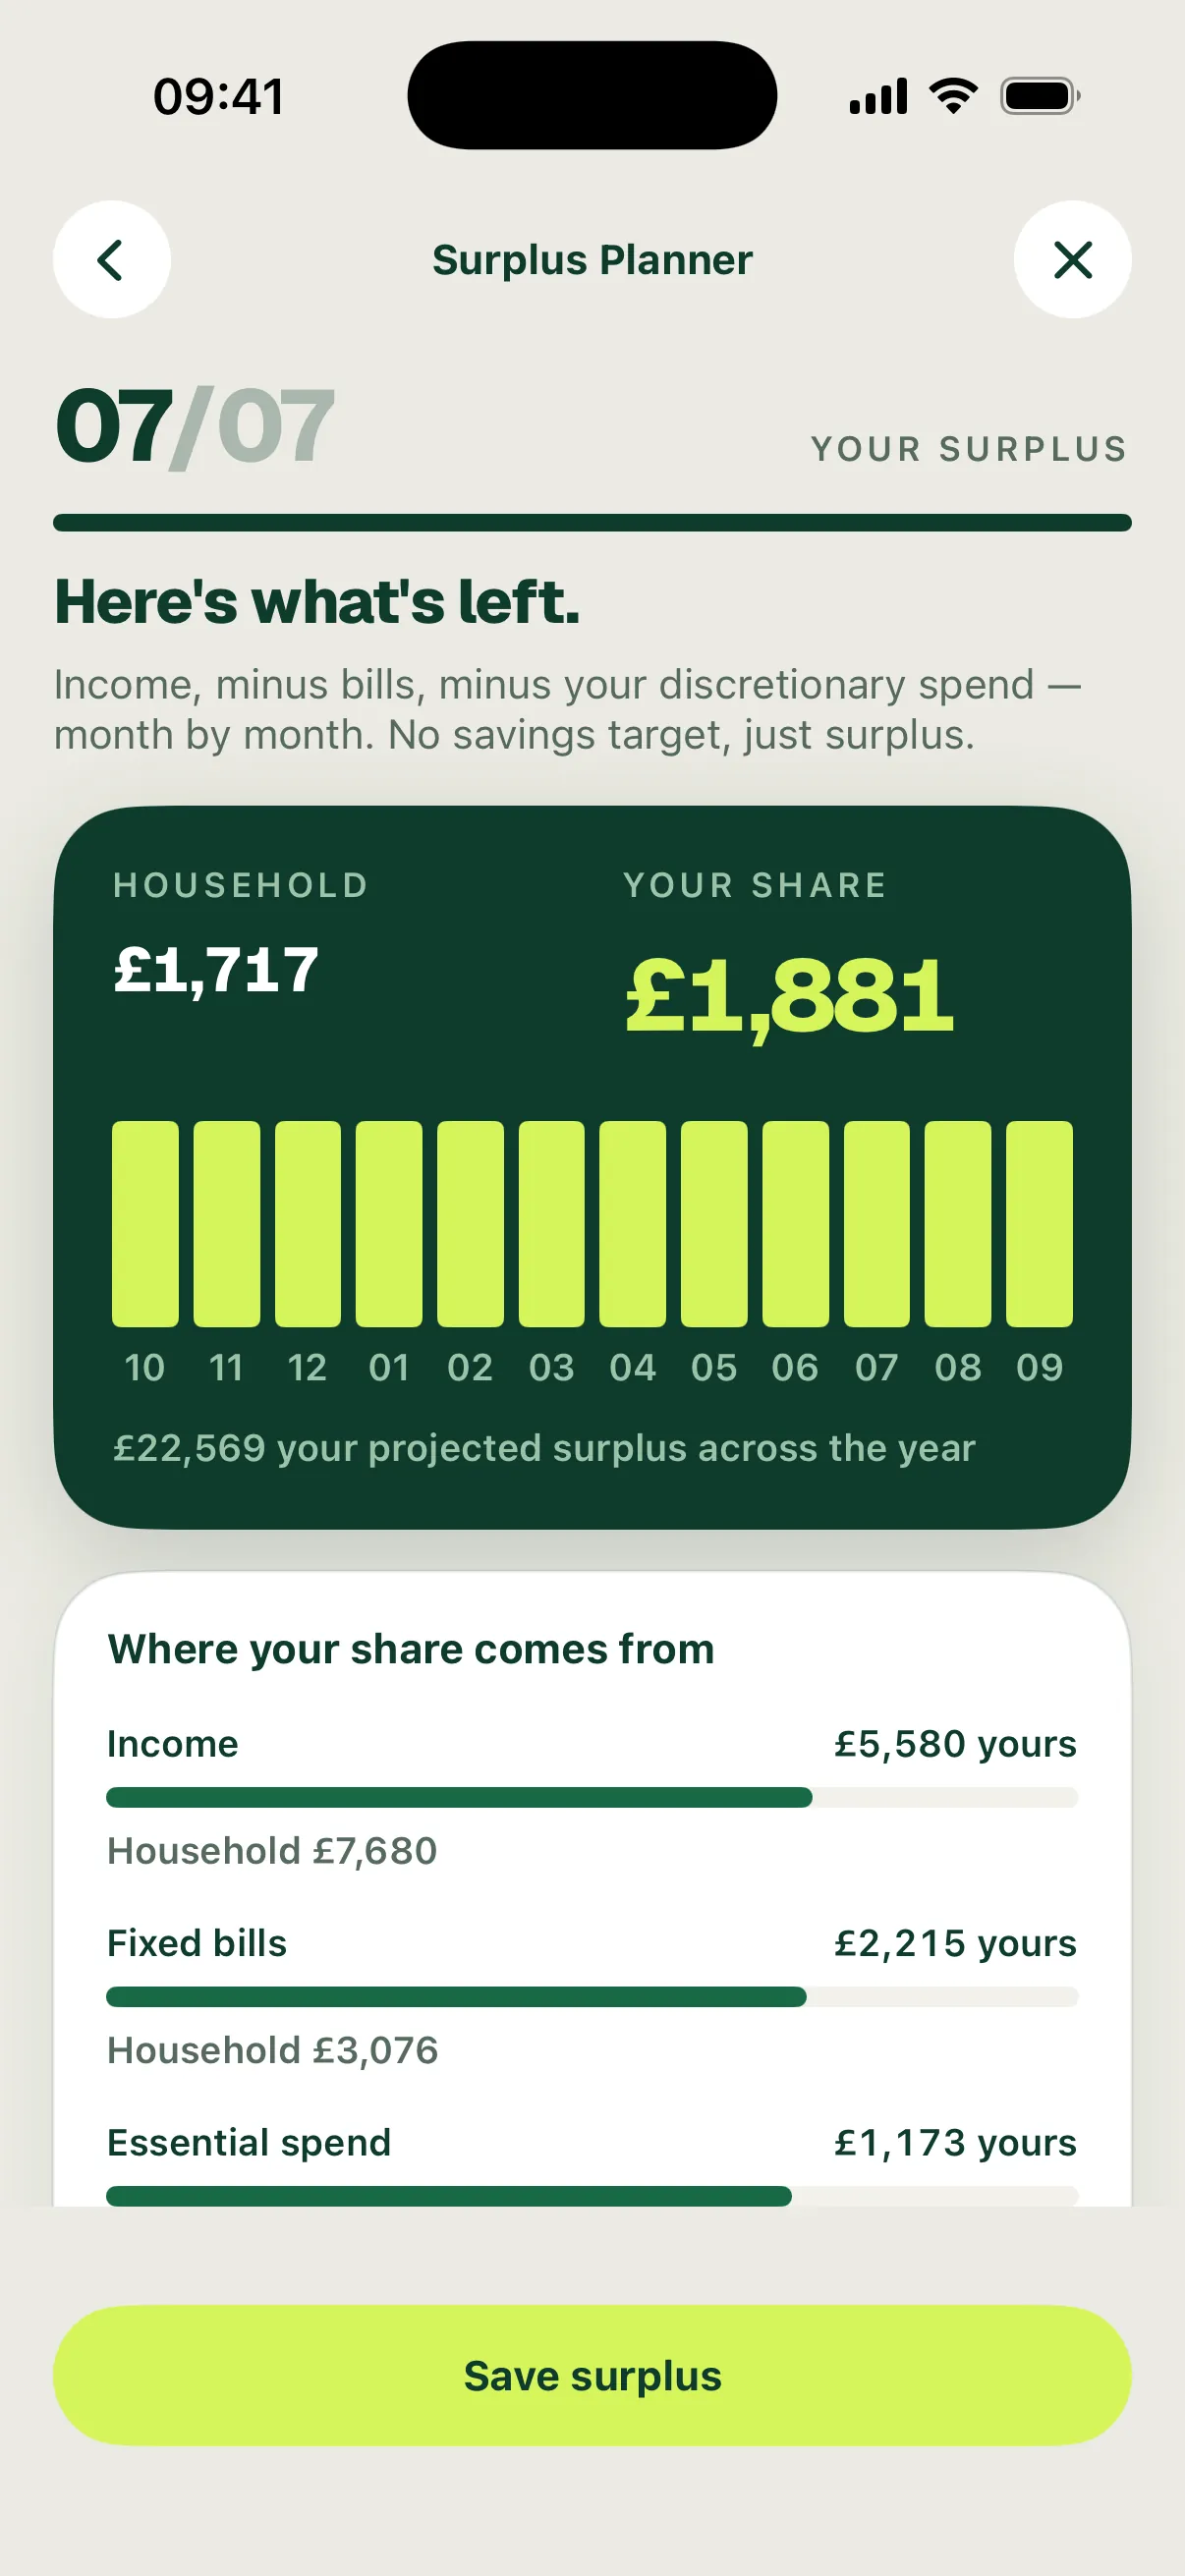
Check the household surplus beside your share, the projected total for the year and Where your share comes from, which shows your part of income, fixed bills, essential spend, discretionary spend and Shared Pool against the household figures. The month-by-month breakdown follows. Then choose Save surplus.
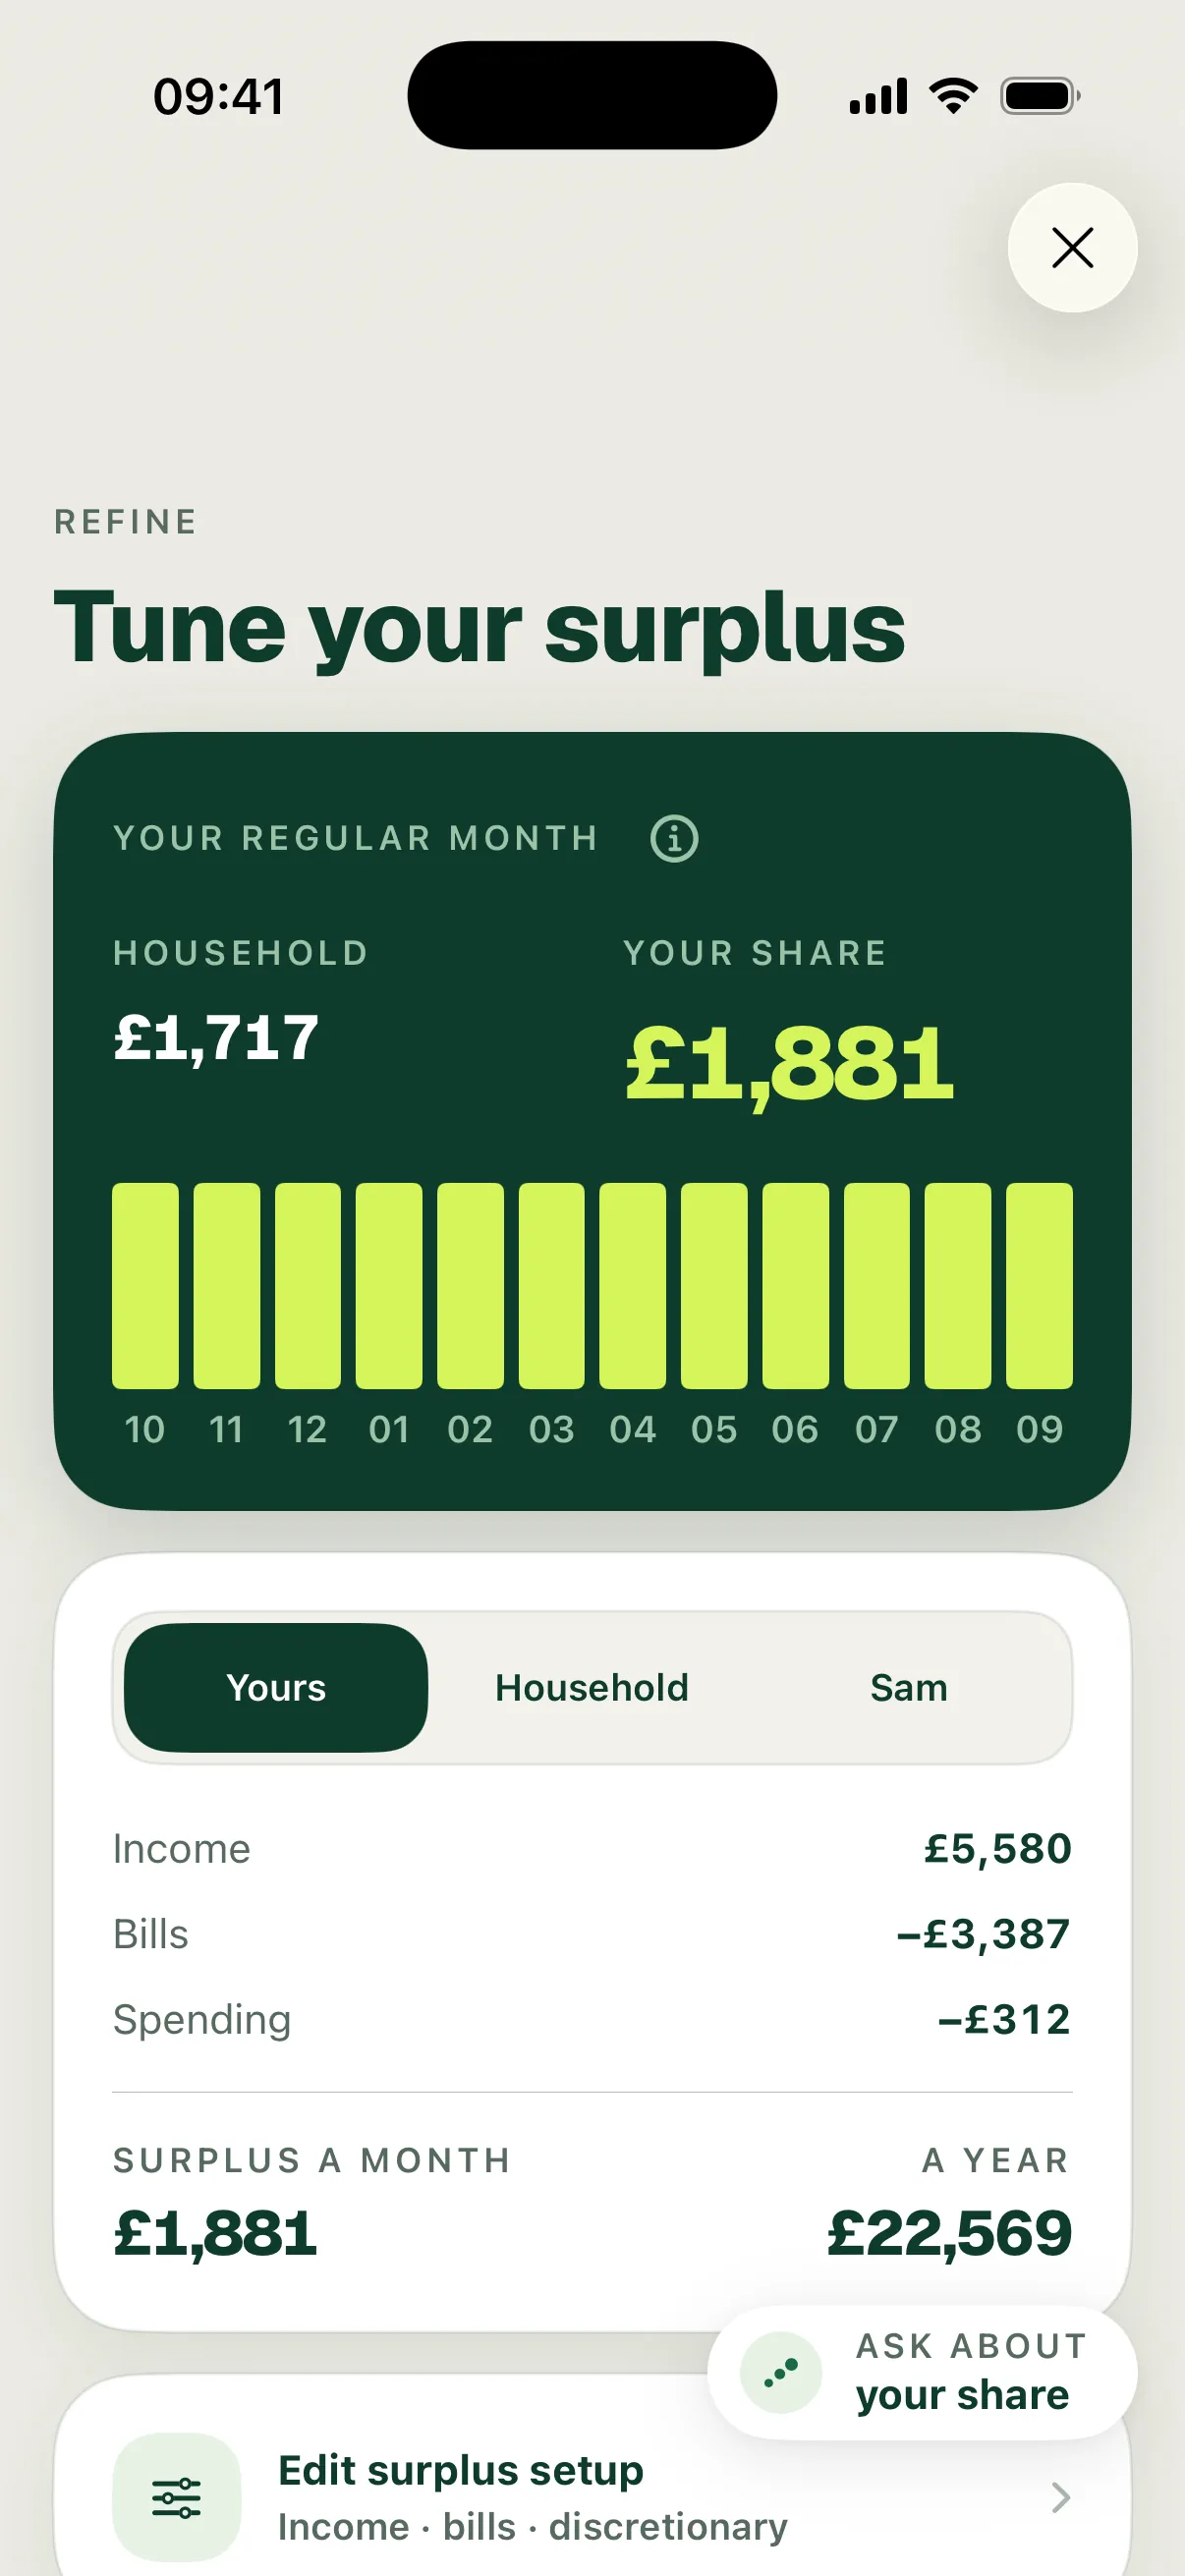
In the example the household is left with £1,717 a month and your share is £1,881, or £22,569 across the year. Your share is higher than the household figure because Sam’s £600 card spending reduces the household surplus but none of it lands in your number. Displayed amounts are rounded; calculations retain pennies.
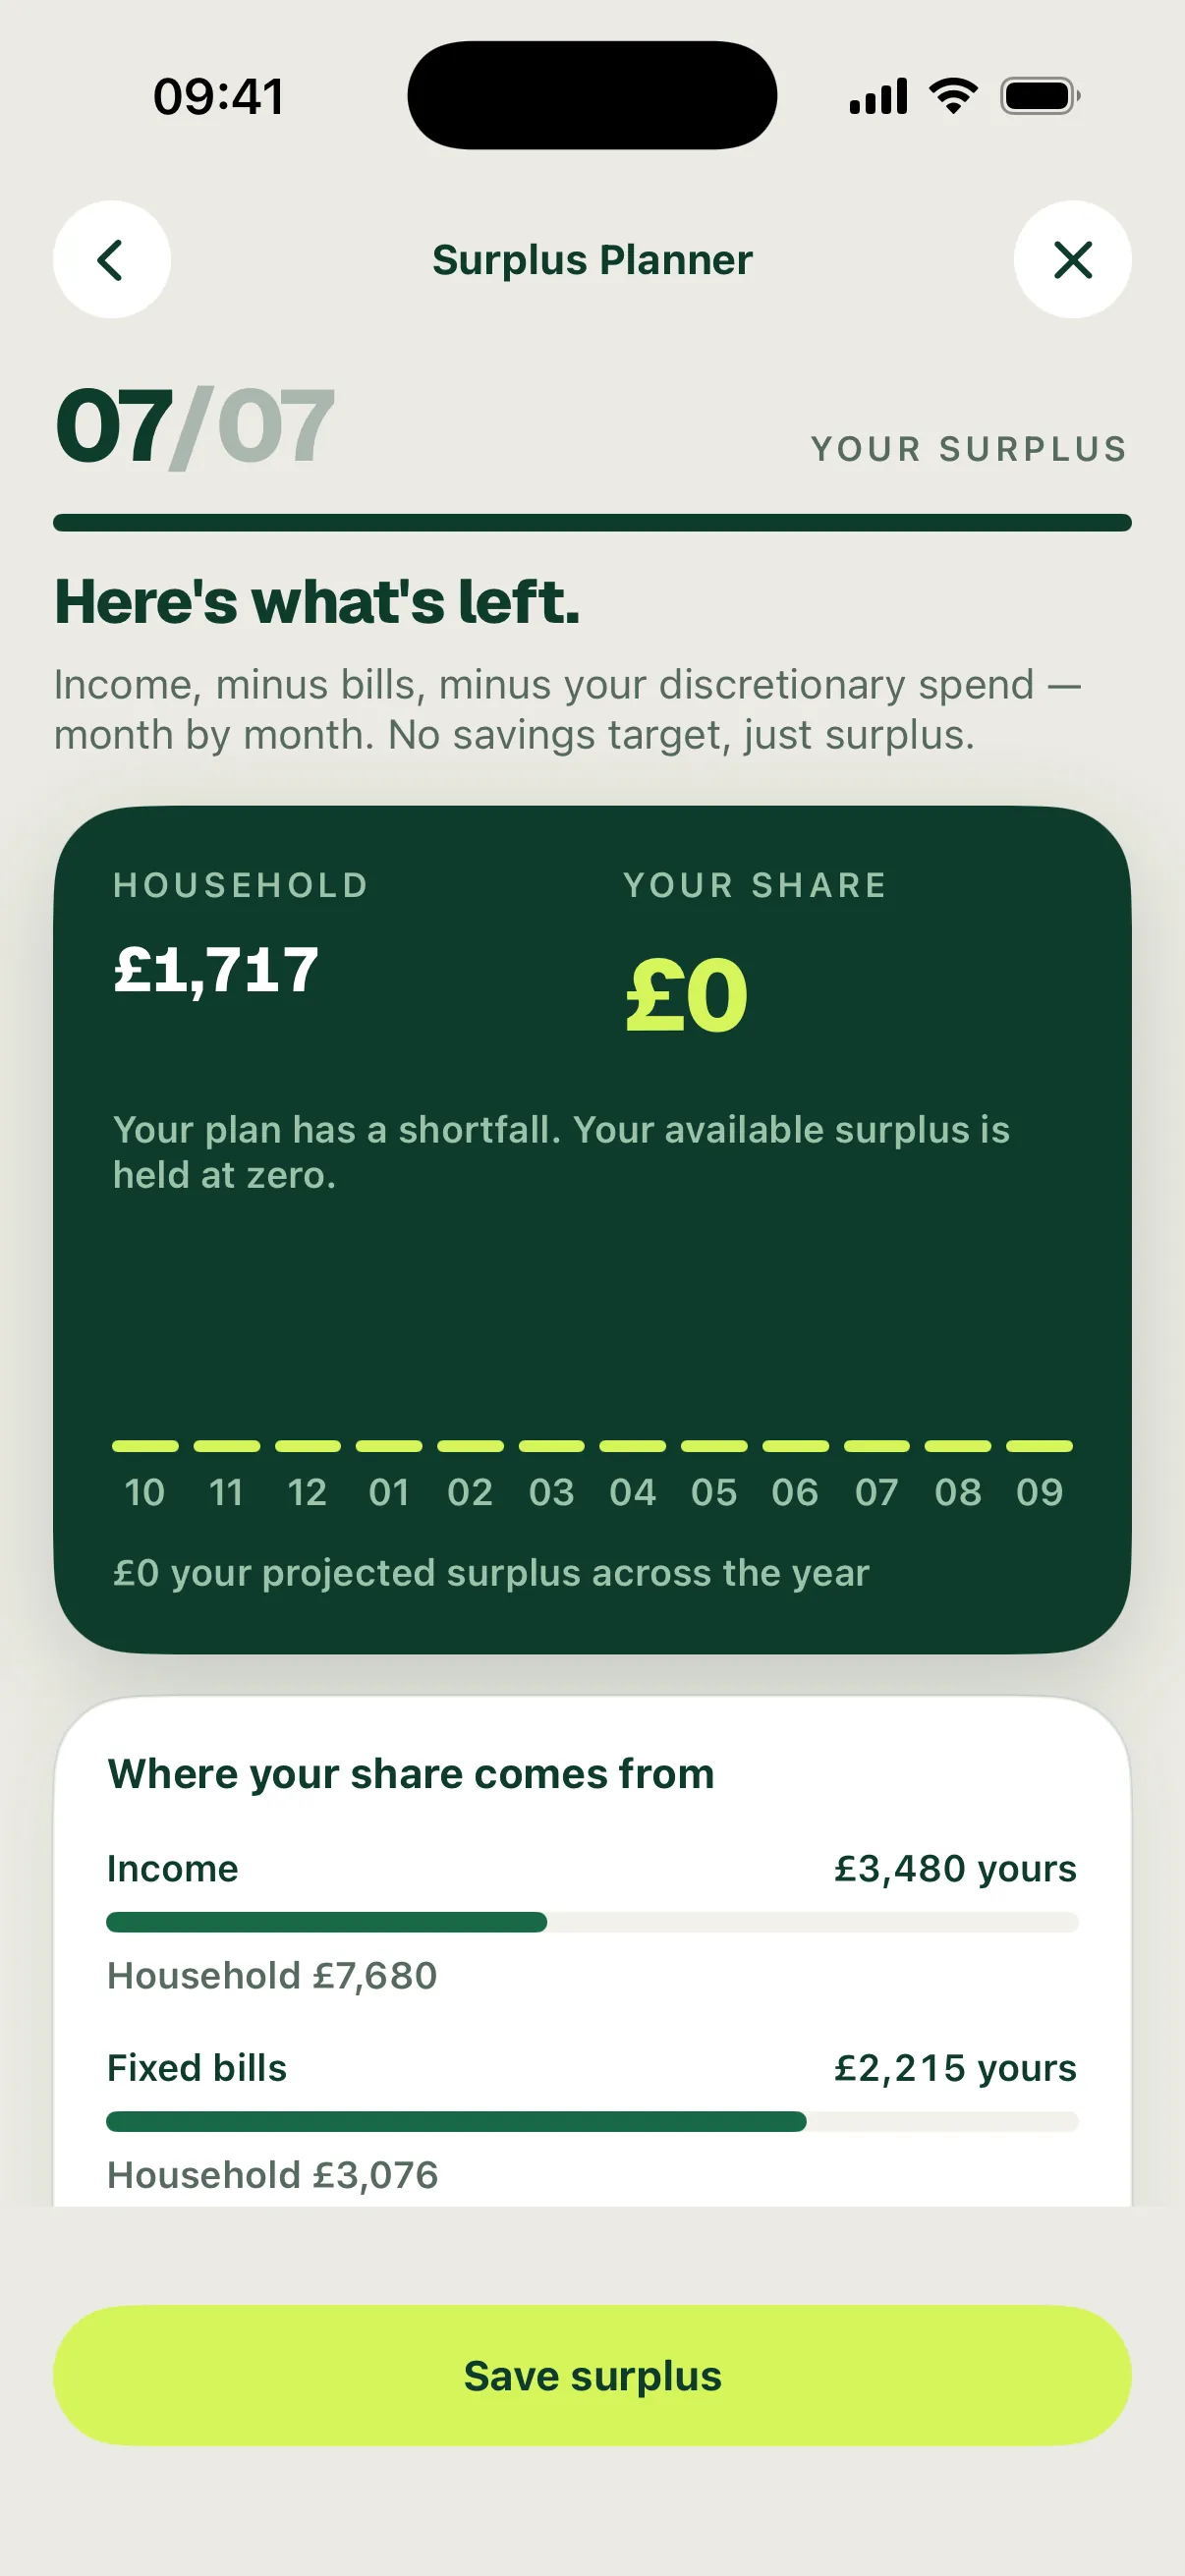
If your share of the bills and spending is more than your share of the income, the step says Your plan has a shortfall and your available surplus is held at zero. Go back and check the shares: in the example this happens when the joint-account salary is tagged as Sam’s while half of the joint bills still count as yours.
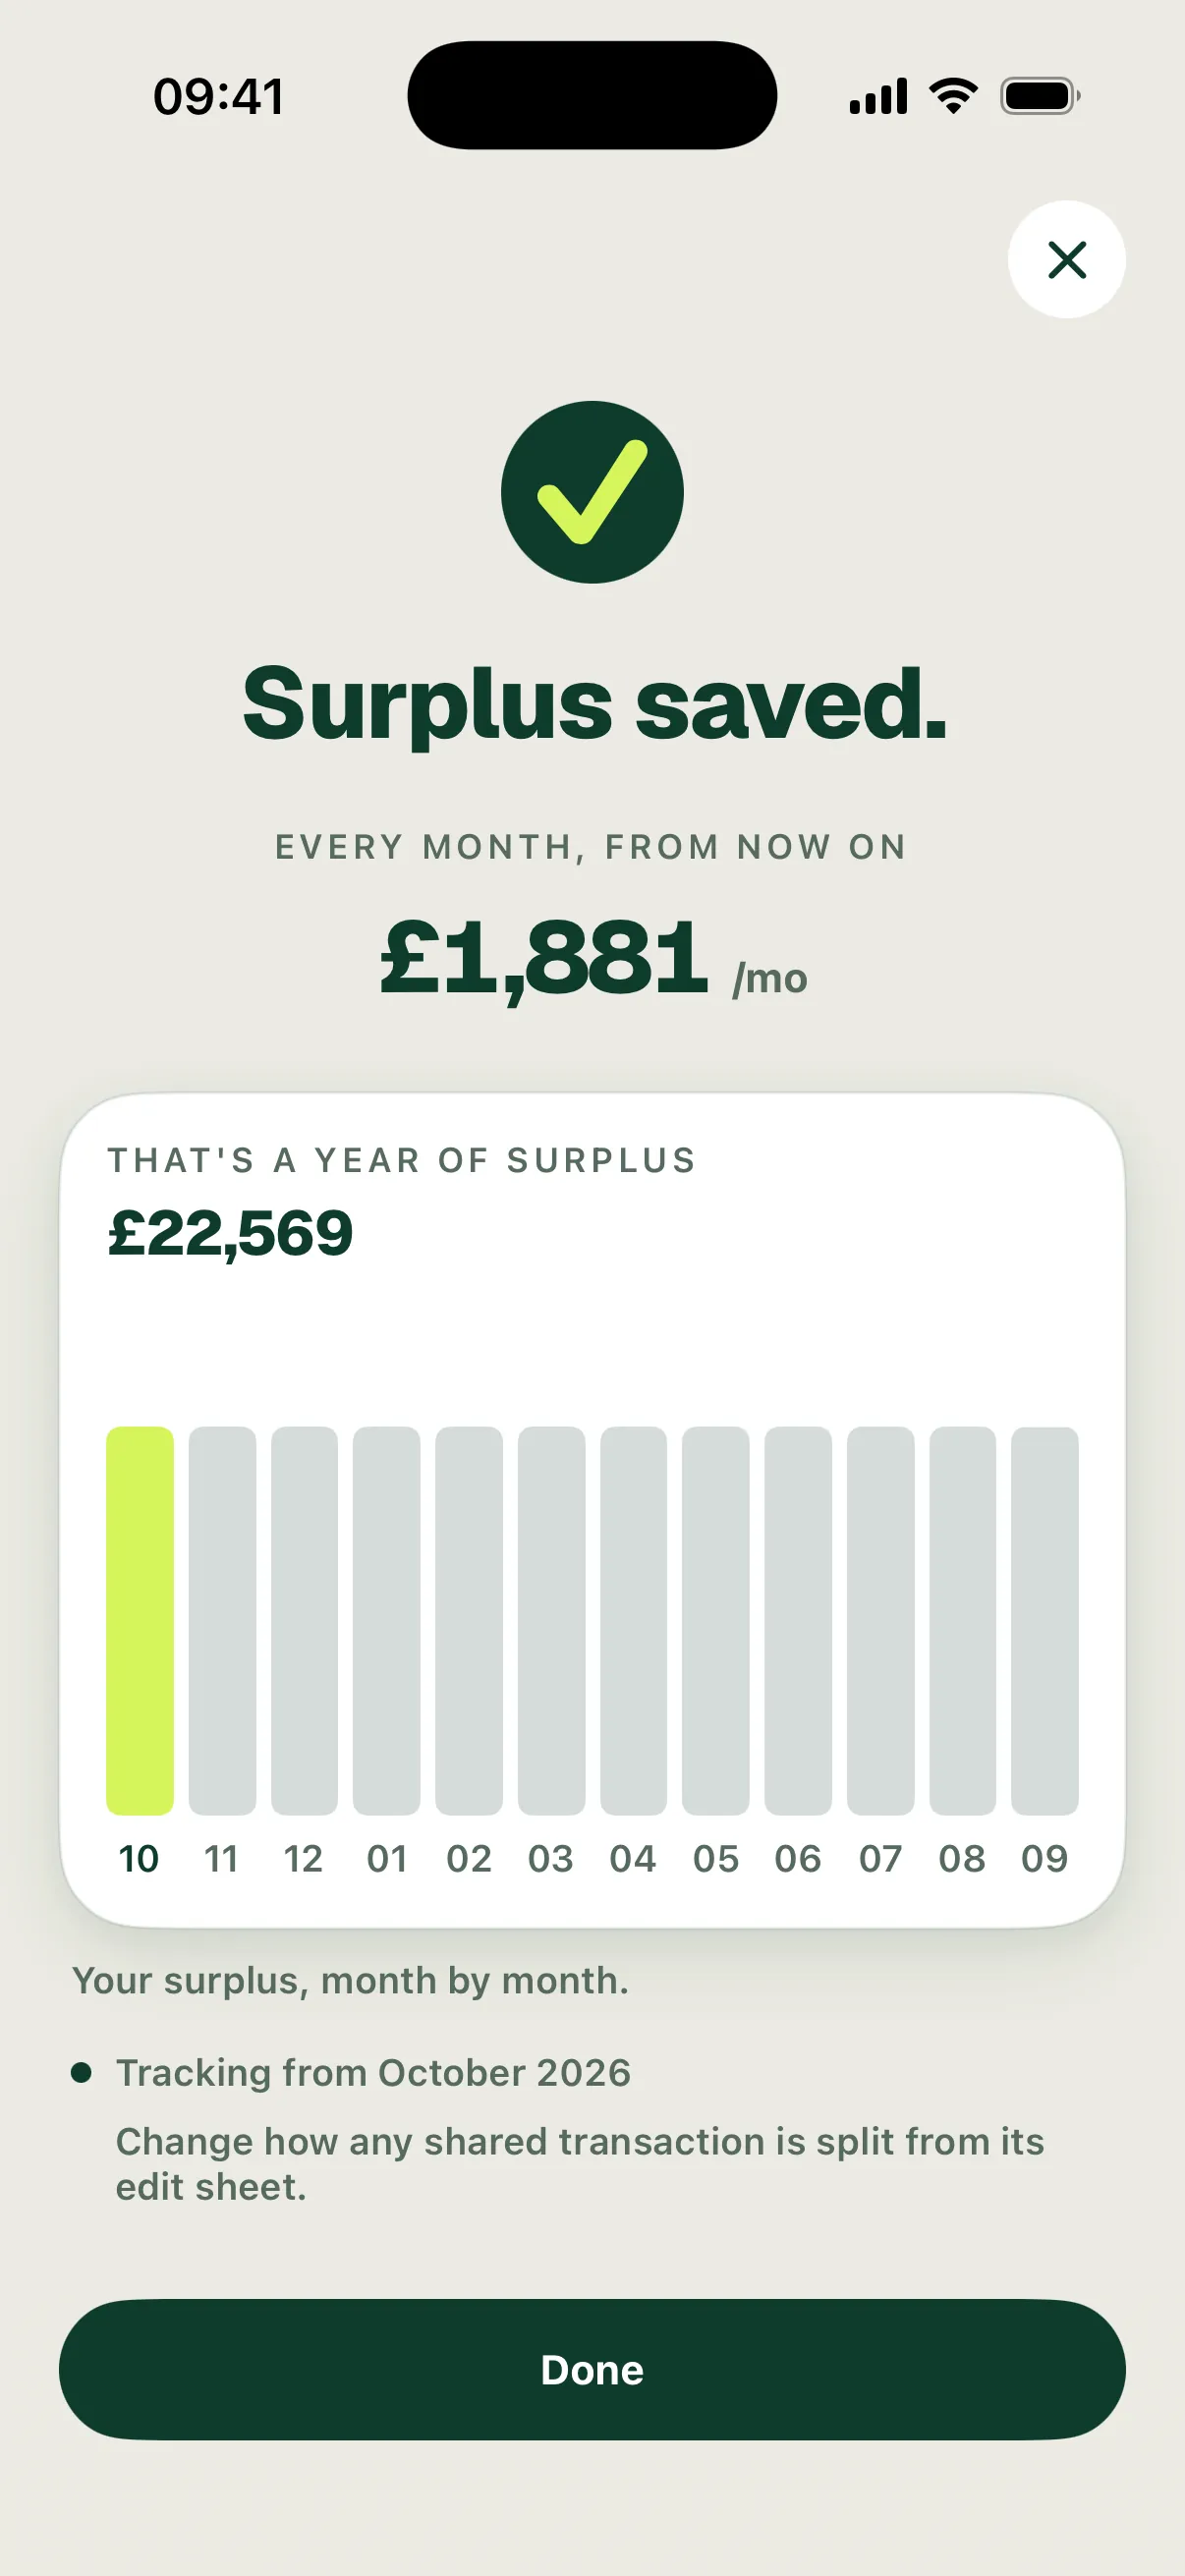
The save confirmation shows your share, £1,881 a month or £22,569 across the year in the example, states that tracking starts in October 2026 and reminds you that any shared transaction’s split can be changed from its edit sheet.
After setup
Growth shows Your regular month with your share of the surplus and the figures behind it. Choose Edit surplus to reopen the planner. The introduction now reads Tune your surplus and offers a Yours, Household or partner view of the same plan, with Edit surplus setup to change any step.